
"Targeting Retirement Age Rather Than Saving 100 Million Won"... 5 Regrets Experienced During the Asset Formation Process in One's 20s
An analysis suggests that the direction of goals and the choice of investment tools during asset formation are key variables in determining long-term asset…
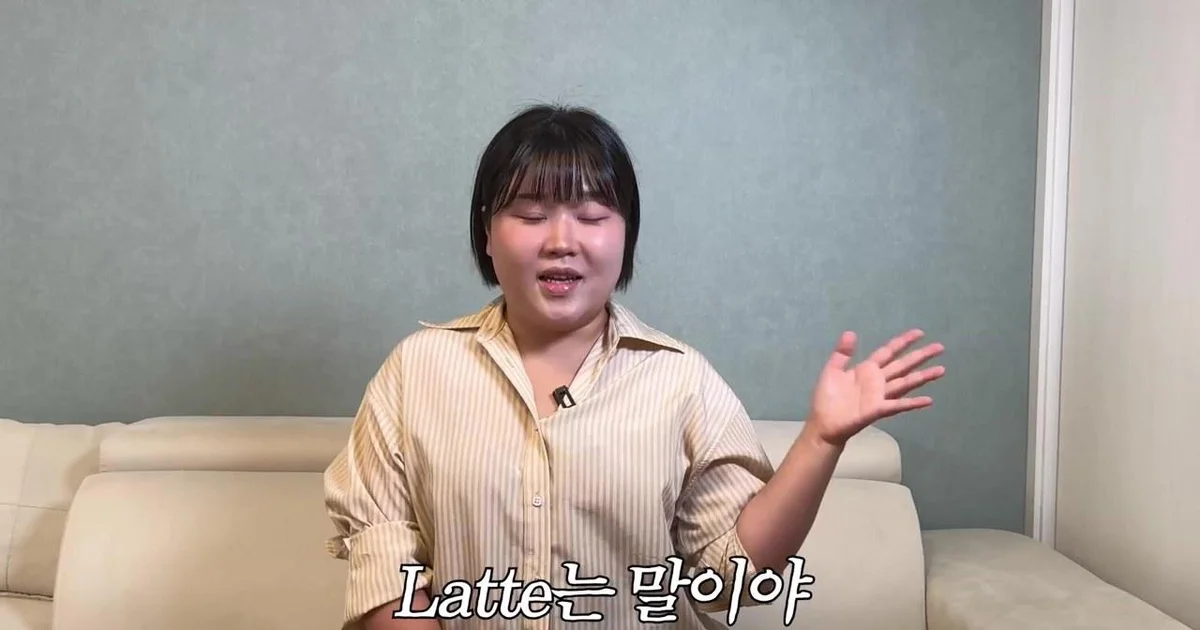
An analysis has emerged stating that the direction of goals set during the asset formation process and the choice of investment tools are key variables that determine long-term asset size. Based on the trial and error experienced during the process of saving 100 million won in one's 20s, the suggestion is that a long-term perspective approach linked to the life cycle is needed rather than goal setting centered on simple amounts.
Need for Goal Setting Centered on 'Retirement Age' Rather Than the Amount of '100 Million Won'
According to the content of a video from the YouTube channel 'Kim Jjanbu', the participant cited making saving 100 million won the top priority in their 20s as one of their biggest regrets. This is because if one becomes immersed in a specific amount like 100 million won, the pressure regarding the direction of asset management increases immediately after achieving the goal, making it highly likely to make inefficient decisions.
The participant recalled that as soon as they achieved 100 million won at the time, they purchased real estate for the purpose of actual residence, but this was a decision made without sufficiently considering personal professional characteristics or the possibility of moving residences in the future. The participant explained, "If I were to go back, I would not have set a goal for the amount of 100 million won, but a goal for retirement age," adding, "The purpose of financial technology should have been placed on preparing for the future rather than becoming an immediate rich person, and I should have established a long plan based on the point in time when money can work for me."
In particular, regarding the purchase of real estate, they warned that a residence-centered choice that did not consider personal professional flexibility could act as a constraint on future asset management (liquidity issues). The participant stated that they purchased a 28-pyeong residential house in Yongin, but overlooked the professional characteristics of needing to move flexibly throughout Seoul as a producer and YouTuber, as well as the life environment that could change in the future. This suggests that during the asset formation period, not only the stability of the residence but also flexible asset allocation reflecting future professional changes or mobility is necessary.
Transition from Savings Centered on Deposits and Installment Savings to Periodic ETF Investment
Regrets regarding the choice of investment tools during the asset formation process were also mentioned. The participant focused more than 90% of the process of saving 100 million won on deposits and installment savings. While there was the stability of principal protection, it was evaluated that there were limits in terms of the speed of asset growth. The participant confessed that while they performed extreme frugality, such as pulling up the savings rate to 88% and commuting between Yongin and Chungmuro for 4 hours round trip, this process instead stimulated a speculative mindset wishing for assets to grow quickly.
The participant said, "If I were to go back, I would have accumulated ETFs periodically like saving in an installment savings account," emphasizing investment using index-tracking ETFs such as the S&P 500 or Nasdaq-100. According to the backtest results mentioned by the participant, if 1 million won per month had been invested periodically, it is estimated that asset formation of approximately 168 million won based on the S&P 500 and approximately 104 million won based on the Nasdaq-100 would have been possible. The participant explained that this not only allows for higher returns than simple savings but is also a process of building the 'compound interest effect' in the brain by increasing understanding of the market.
However, the participant added that exceptional products that provide tax-free benefits and government contributions, such as the Youth Leap Account or Youth Hope Savings, which are government-supported products, are healthy savings tools that can secure both principal protection and high interest rates simultaneously.
Preference for Items with Practical Value Over Cash Gifts
A changed perspective was also presented in terms of consumption and gifts. Regarding the method of gifting cash to parents or family, the participant regretted it, saying, "It feels like it doesn't leave a memory and disappears into thin air." They pointed out that since cash is consumed as living expenses immediately after receipt and disappears, it is difficult to remember the giver's heart for a long time. In fact, mentioning cases where people gifted cash but were unable to buy the same item again due to inflation after time had passed, they advised, "A gift is cheapest when you decide to buy it."
The alternative presented is 'practical items with high satisfaction that are used every day.' As criteria for gifts for the elderly, the participant picked: ▲things used every day, ▲things that help with physical convenience, and ▲high-quality home appliances that are difficult to purchase readily with one's own money. In particular, they explained that products like cordless vacuum cleaners, which reduce the user's physical burden (waist, knees, etc.) while making one think of the giver every time they are used, have high value as filial piety gifts.
In the case of the cordless vacuum cleaner mentioned as a specific example, the advantages cited were that it reduces physical burden by eliminating the hassle of plugging and unpluging cords, and can maximize user convenience through the function of automatically emptying the dust bin. Additionally, they added that products including lighting functions to easily check dust for elderly people with weak eyesight could be a choice that satisfies both practicality and satisfaction.
0Comments
Comments are currently disabled.