
Tax Office Notice for Submitting Clarification Materials: 3 Precautions When Responding to the 'Pre-Tax Audit Stage'
Self-employed individuals and business owners receiving notices to submit clarification materials should treat them as a critical pre-audit stage.
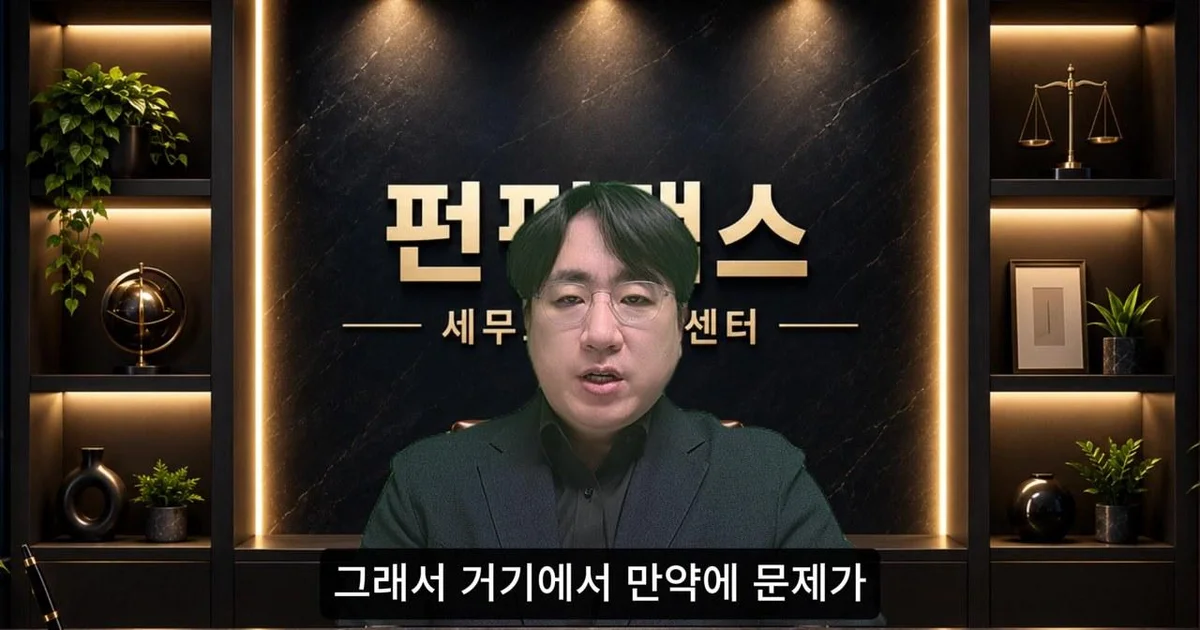
Self-employed individuals and business owners who receive a 'Notice for Submitting Clarification Materials' from the tax office must not dismiss it as a simple inquiry. This notice is classified as a pre-tax audit stage, and the way one responds can determine whether it leads to a future tax audit. According to a video from the YouTube channel 'Semujosa-neun Peonpeontaekseu | Guksecheong Josaguk Chulsin', correct response principles and precautions to take immediately after receiving the notice have been presented.
"Do not try to explain things that were not asked"
The most important precaution when submitting clarification materials is not to voluntarily provide information that the tax authorities did not request. The presenter in the video advised being wary of attempts to explain by submitting materials related to parents, family, or related companies out of anxiety upon receiving the notice. This is because tax authorities often already have the necessary information, and if materials are submitted beyond the requested scope, there is a risk that the demand for clarification may expand to those subjects or lead to a tax audit.
Therefore, it is important to answer accurately only regarding the questions and the scope of requests specified in the notice. The presenter emphasized, "You should only answer what is asked," stressing that clear explanation of the requested items takes precedence over excessive explanation. In particular, he pointed out that attempts to appeal as a high-income earner through a Certificate of Income Amount are also of low effectiveness. The presenter explained, "Even if you assume you earned 500 million won, if you spent 490 million won, the remaining amount is only 10 million won," noting that the National Tax Service already understands the relevant details, so proving income alone is not a sufficient explanation.
Short submission deadlines and how to use 'deadline extensions'
A notice for submitting clarification materials usually grants a short period, ranging from 3 days to as long as 15 days. During this period, it is easy to feel flustered as one often has to explain bank transfer details or cash transaction details spanning from 1 to as many as 5 years. There are frequent cases where people feel lost because the notice only lists account numbers or lists multiple amounts that need to be explained.
If the notice was checked late due to reasons such as a mismatch in address or a business trip, it is advisable to immediately explain the circumstances to the ice in charge (in-charge) tax official and request a deadline extension. According to the presenter, if you explain the reason and request an extension, it is accepted in most cases. Caution is required because if you miss the deadline due to not receiving the notice, the in-charge tax official may judge that there is no data or no intention to explain.
Furthermore, receiving a notice does not necessarily mean there is a problem, but things such as the source of funds in the process of acquiring real estate, large bank transfer details, or cases where large sums of money are transferred relative to one's age are major targets of interest for tax authorities. In particular, cases of receiving such notices are frequent for 'document fraudsters' who issue false fabricated invoices. For self-employed individuals, it is good to consult with their usual bookkeeping tax accountant, but the presenter mentioned that if cases involving suspected omission of sales or use of borrowed-name accounts are included, there is a high possibility that even the bookkeeping tax accountant may not know the details.
Key is 'documentary evidence' rather than verbal explanation
Explaining the situation with logical words during the clarification process does not provide practical help. The presenter explained, "No matter how well you speak, it is useless," and stated that one must provide evidence with objective documents. All explanations must be supported by documents following the proper format, and if documents are prepared falsely or with lies, it can escalate into larger tax problems.
Meanwhile, unlike a tax audit, a separate document notification regarding whether the case is closed often does not come when submitting clarification materials. Rather than concluding that the situation is completely over just because it is quiet after submission, one should prepare thoroughly with the possibility in mind that it may be reviewed again within the next few years. The presenter added, "Submitting clarification materials is not a tax audit, but it can be as detailed and difficult as a tax audit," and "A tax audit has an end date, but clarification materials have no end date (through deadline extensions, etc.)." Therefore, the presenter's advice is that thorough preparation equivalent to a tax audit is required.
0Comments
Comments are currently disabled.