
"Demand Deposit 0.1% vs CMA 2% range"... The first thing novice investors should do
A step-by-step account management strategy is presented for novice investors lacking financial knowledge, emphasizing the importance of moving funds from low-yield bank accounts to CMA accounts and managing essential accounts based on life cycles.
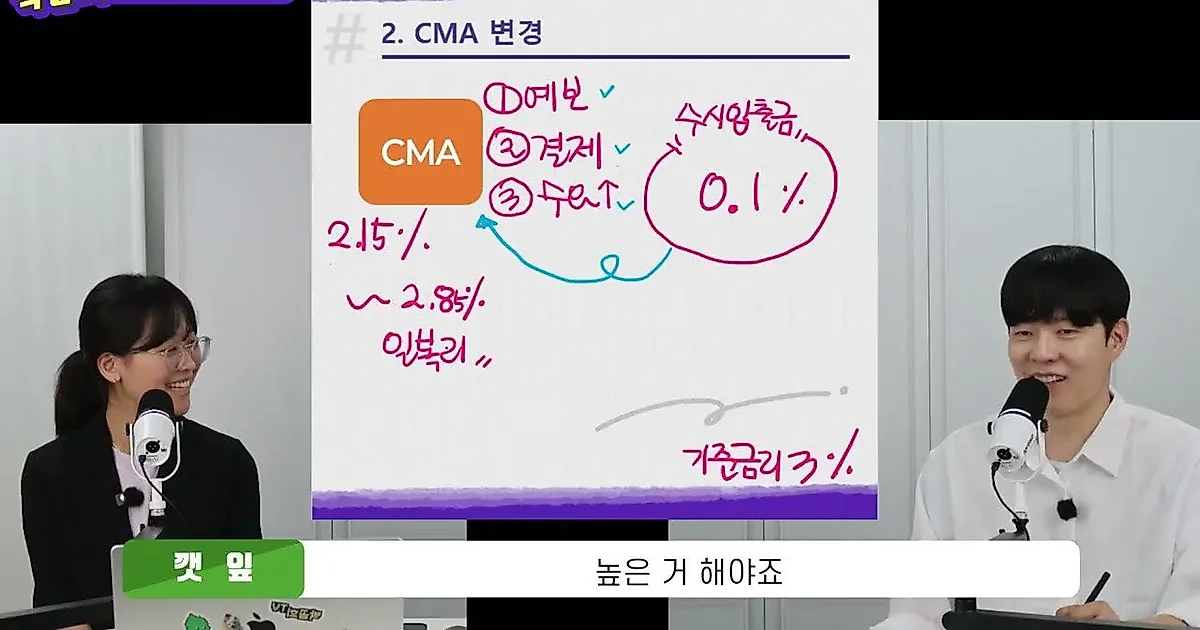
The first problem novice investors who intend to start investing face is not knowing what to start with and how to start. For beginners who lack financial knowledge or experience using securities firms, a step-by-step account management strategy has been presented.
"Just open one first"... 5 essential accounts by life cycle
The first step of investing is opening an account. In the video, it recommends opening an account first without a process of persuading investment, and explains account management methods according to age group and life cycle. For those new to society, it is basic to operate centered around three types of accounts: CMA, ISA, and pension savings. The method is to move the remaining funds after receiving a salary to a CMA, utilize an ISA to prepare a lump sum, and open a pension savings account for tax credits. The purpose of an ISA is to create a lump sum by setting up investments with low negative risk within 3 to 5 years.
As age increases, additional accounts are needed. If one wishes to increase tax credit benefits after their 40s, it is recommended to add an IRP (Individual Retirement Pension) account in addition to pension savings. Subsequently, at the retirement point in their 50s and 60s, a retirement IRP for receiving severance pay is essentially added. As a result, the essential accounts to be equipped from being a newcomer to the time of retirement are summarized as at least 5 (CMA, ISA, pension savings, IRP, retirement IRP). Other than these, brokerage accounts for active investing and KRX gold spot accounts with tax-exempt benefits are classified as optional areas.
The yield gap between bank demand deposit accounts and CMA
The key task after opening an account is switching to a CMA (Cash Management Account). The video pointed out the difference in yield between a general bank demand deposit account and a CMA. In a situation where the base interest rate is at the 3% level, the yield of a general bank demand deposit account (ordinary deposit) often stays in the 0.1% range. On the other hand, a CMA can provide a much higher yield than this.
The reasons why large amounts of funds stay in bank demand deposit accounts are cited as the depositor protection system and the convenience of payment functions. While there are differences such as the fact that a securities firm's CMA is not protected by depositor protection unlike a bank, and differences in payment functions, the analysis shows that utilizing a CMA is advantageous in terms of yield. In particular, to increase returns while securing liquidity without tying up investment funds in savings and installment deposits, the use of a CMA is necessary.
The complexity of bond trading and the necessity of account management
The difficulty of bond trading felt in actual financial fields was also mentioned. Unlike stocks, bonds are characterized by the fact that searching for items is difficult, and even for bonds issued by the same company, numerous items exist depending on the conditions, causing intense scrolling pressure. Also, because the quantity unit calculation method for bonds is different from stocks, the trading method may be unfamiliar. Due to this fragmented financial information and complex trading environment, the core point is that novice investors should start with immediately actionable account opening and management before looking at macroeconomic indicators.
0Comments
Comments are currently disabled.