
Startup subsidies may be included in business income... Proof of expenditure is key to tax saving
Startup subsidies provided by the state or local governments may be treated as business income, making the management of expenditure proof essential for tax reduction.
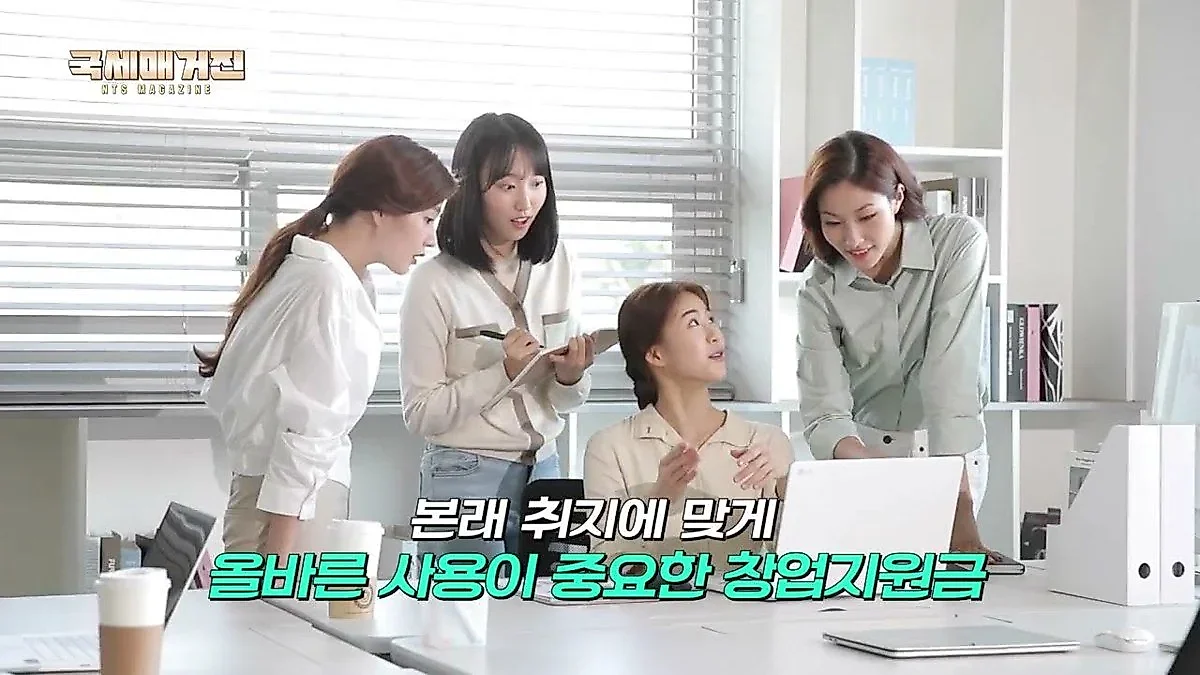
Between the 'merchant apprenticeship system' used by Gaeseong merchants in the Joseon Period to select talented youth and teach them the basics of business, and the 'startup subsidies' received by today's young entrepreneurs, there is a common context of nurturing talent and settling businesses. However, modern startup support comes with the practical task of tax management.
According to the National Tax Magazine reported by the National Tax Service, in the past, Gaeseong merchants selected young and capable youths as commercial apprentices called 'sahwan' and conducted systematic training. The apprentices learned the basics of business one by one, such as bookkeeping, handling goods, and customer service. After completing practical training, the apprentices grew into 'chain' and could start independent commercial activities in other regions, sometimes even expanding their businesses by borrowing funds from the 'owner.' This was a unique talent nurturing method of the Gaeseong merchants that expanded their organizations by raising new merchants.
Startup subsidies are not unconditionally tax-exempt... Principle of inclusion in income
Times have changed, but the trend of supporting new merchants continues. Representative examples include various support programs provided by the state and local governments, such as the 'Youth Startup Academy' or 'Pre-Startup Package' for young entrepreneurs. A point where many entrepreneurs easily become confused here is the issue of taxation.
The National Tax Service explains that startup subsidies received from the state or local governments may be included in income when calculating business income. The video specified that while it is easy to think of subsidies as funds unrelated to the business, under tax law, subsidies related to the business can also be considered part of the business income. In other words, the act of receiving a subsidy itself can be subject to tax calculation.
Proof of expenditure is the key to tax saving... Taxes vary depending on whether expenses are recognized
Just because subsidies are included in income does not mean taxes are levied on the entire amount received. The key lies in how the subsidies were used. If the subsidies are used for business purposes and this can be proven, the amount can be recognized as an expense (necessary expense) under tax law.
For example, if the subsidies were used to purchase equipment necessary for the business or to pay employee wages, these business-related expenditures can be reflected as expenses when calculating income. The National Tax Service explained that even if the amount of subsidies received is the same, the final tax burden can vary depending on how they are used and whether they are recognized as expenses under tax law.
Importance of proof management for stable business operation
Therefore, entrepreneurs must thoroughly manage materials that can prove usage details, such as receipts, from the moment they receive the subsidies. As startup subsidies are funds designed to help the new challenges of young people and support stable business operations, it is important to use them in accordance with the original purpose of the subsidies. The National Tax Service emphasized that meticulously managing everything from receipts to the actual usage stage becomes a solid foundation for starting a business.
The National Tax Service stated that the process of entrepreneurs learning business registration, tax filing, and various tax benefits one by one will serve as a strong foundation for the business. Furthermore, just as King Sejong created Hangeul so that anyone could easily learn to write, the National Tax Service expressed its intention to support young entrepreneurs so they can easily understand and utilize the tax system, which they may find difficult.
Source: original video (YouTube)
0Comments
Comments are currently disabled.