
Low-Price Sales Between Parents and Children: Beware of Gift Acquisition Tax Surcharges if the '300 Million Won' Threshold is Exceeded
The article explains the tax risks and strategies involved in transferring property between parents and children through gifts, sales, or encumbered gifts…
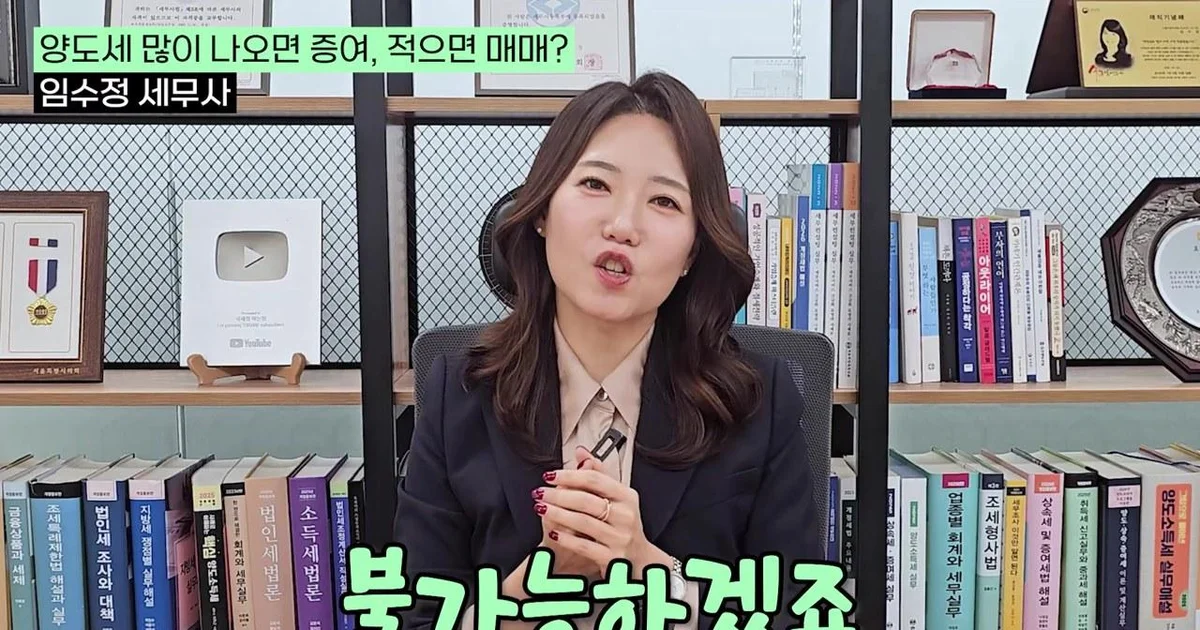
The methods by which parents pass down houses to their children are largely divided into gifts, sales, and encumbered gifts, which involve transferring debt along with the property. Due to recent tax reforms and changes to the Enforcement Decree of the Local Tax Act, the tax risks to consider during family transactions have increased. According to a video from the YouTube channel 'Segeum Aneunhyeong', because the taxpayer and the applicable tax rates change completely depending on the method of asset succession, sophisticated planning is required.
Gifts, Sales, and Encumbered Gifts: Who Pays Which Tax?
If a parent transfers a house to a child without any consideration, it constitutes a 'gift'. In this case, since the child has acquired property for free, they must pay gift tax, and since they are acquiring the house under their own name, they also bear the obligation to pay acquisition tax. Regarding gift tax, if the 'installment payment system' is utilized, one can pay one-sixth at the time of reporting and divide the remainder into six total installments over five years, making it easy to establish a payment plan if the child has sufficient income. Additionally, since there is no obligation to reside in the property for a gift, it is possible to lease the gifted house out and use the lease deposit to pay the gift tax.
On the other hand, in the case of a 'sale' where the house is sold for money, the parent who receives the money bears the capital gains tax, and the child who buys the house bears the acquisition tax. If the house is sold too cheaply compared to the market value, the difference may be considered a gain for the child, leading to additional gift tax being imposed. An 'encumbered gift', which includes transferring debt, is a hybrid form of gift and sale. For example, if there is a 2 billion won apartment with a 1 billion won lease deposit, the child pays gift tax on the 1 billion won excluding the debt, and the parent pays capital gains tax, as the 1 billion won debt portion is viewed as being transferred for consideration. In this case, different acquisition tax rates are applied to the debt portion (for consideration) and the gift portion (free of charge).
However, houses located in land transaction permit zones within adjustment-target areas, such as Seoul, trigger an obligation to reside in the property during a sale or encumbered gift. The video explained, "If residing is difficult (e.g., a child living abroad), sales and encumbered gifts are impossible, and pure gift is the only option." However, since the system changed starting this May to allow non-homeowners buying a house with a tenant to delay moving in for up to two years until the tenant's contract ends, children who are non-homeowners should first check the real estate permit requirements.
The '300 Million Won' Threshold and Variables in Joint Ownership Between Spouses for Low-Price Sales
The most important point to note during low-price sales between family members is the '300 million won difference'. Under the current Inheritance Tax and Gift Tax Act, if the difference between the market value and the transaction price is less than 300 million won, no gift tax issue arises. However, according to the Local Tax Act amended this year, if the difference between the market value and the consideration is equal to or greater than the smaller of '30% of the market value' or '300 million won', it is considered a 'gift' rather than a sale, and the gift acquisition tax rate is applied. In particular, caution is needed as the acquisition tax rate can soar up to 12% when gifting a house with a standard market value of 300 million won or more within an adjustment-target area. Therefore, even in an adjustment-target area, a gift can be actively considered if the standard market value is less than 300 million won.
Tax-saving strategies using joint ownership between spouses were also mentioned. When interpreting the provisions of Article 35 of the Inheritance Tax and Gift Tax Act (Gift of Profits due to Low-Price Acquisition), judgment is made per acquirer; thus, the video explains that if a married child couple buys a house under joint names, it can be structured so that the son and daughter-in-law each buy it 300 million won cheaper (total 600 million won) than the market value, thereby avoiding gift tax issues. However, according to the Enforcement Decree of the Local Tax Act implemented on June 1 this year, when a share is acquired, it is viewed as having acquired the entire share when calculating the difference; therefore, even in joint ownership between spouses, the transaction price must be finely adjusted so that the difference for the entire share does not exceed the '30% of market value or 300 million won' threshold.
Furthermore, it is risky if the child's source of funds is unclear during a low-price sale. For example, selling a 1 billion won apartment for 710 million won, paying only 200 million won and borrowing the remaining 500 million won from the parent by writing a promissory note, is a transaction method that is not recommended, even if it is a use of a system permitted within the scope of tax laws. The video emphasized, "Instead of a promissory note, ensure the payment is made clearly with your own money."
If Parents Own One House, 'Low-Price Sale' Could Be the Optimal Alternative
The video analyzed that if parents meet the tax exemption requirements for a single household with one house, a low-price sale can be a very efficient means of asset succession. This occurs when parents intend to downsize their housing after retirement and children intend to move to a higher-tier area, transferring the house to the child at a price lower than the market value. This structure is advantageous because if the parents are single-household one-house owners and receive the special deduction for long-term holding (up to 80%), the capital gains tax burden is not heavy. The child can acquire the asset without the burden of gift tax, and can even expect inheritance tax saving effects in the future.
However, it should be noted that during the transaction, if the difference between the market value and the transaction price is 5% of the market value or 300 million won or more, the parents must report capital gains tax based on the market value (denial of unfair act calculation rule), and the child must also pay acquisition tax based on the market value recognition amount. In conclusion, one must decide between a gift and a sale by comprehensively considering whether the parents own one house, the child's ability to mobilize funds, and whether there is an acquisition tax surcharge in the relevant area.
0Comments
Comments are currently disabled.