
If Interest and Dividends Exceed 20 Million Won, It's a 'Tax Bomb'... Avoid Comprehensive Financial Income Tax Using ISA and Pension Savings
When financial income exceeds 20 million won per year, it is subject to comprehensive financial income taxation…
Care is required because when financial income exceeds a certain level, not only do tax rates rise sharply, but the burden of health insurance premiums can also increase. This is because if interest and dividend income exceed 20 million won per year, it becomes subject to comprehensive financial income taxation and is combined with other income, such as earned income.
If Interest and Dividends Exceed 20 Million Won, They Convert to 'Comprehensive Income Tax'... Health Insurance Burden Also Increases
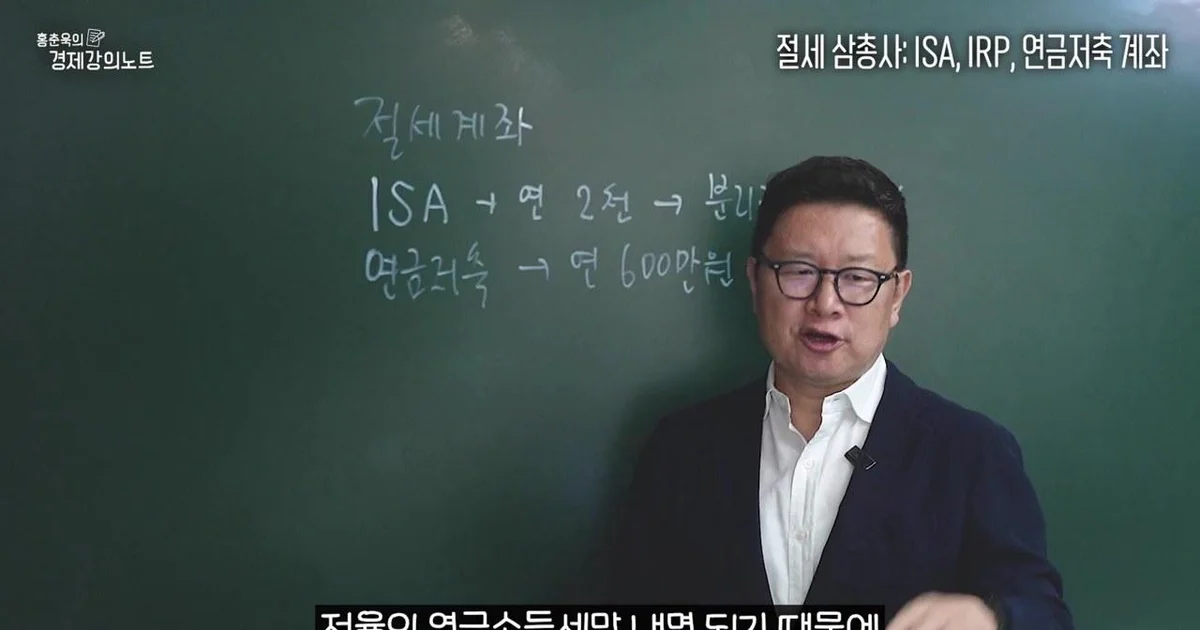
Generally, a tax rate of 15.4% is applied to stock dividends or interest income. However, the moment financial income exceeds 20 million won per year, the problem becomes complicated. According to a video from "Hong Chun-uk's Economics Lecture Notes," if financial income exceeds 20 million won, it converts to a target for comprehensive financial income taxation, where that income is combined with earned income and others. In the past, the threshold for comprehensive financial income taxation was 40 million won, but it has now dropped to 20 million won, and there are concerns that it could drop as low as 10 million won in the future. In this case, depending on the income level, the applied tax rate rises to a progressive tax rate that is much higher than 15.4%. For example, the difference in tax burden is distinct when compared to the tax bracket applied when income is 88 million won or less.
In particular, it is not just taxes that one should be careful about. The video emphasized that if one becomes subject to comprehensive financial income taxation, health insurance premiums can rise significantly. The presenter cited his own past experience as an example, mentioning a situation where his interest and dividend income exceeded 20 million won while managing assets through dividends and special term deposits after retiring (FIRE) at the end of 2018. He explained that because other income from book sales was also combined, comprehensive income tax was levied, leading to high tax rates and the burden of paying millions of won in health insurance premiums every month, advising that "for those planning retirement, managing comprehensive financial income taxation is essential."
ISA, Pension Savings, and IRP: What are the Characteristics and Priorities of Each Account?
The key means to reduce this tax burden is to utilize tax-saving accounts. The video compared the characteristics of three accounts: ISA, Pension Savings, and IRP.
First, the ISA is considered the most important account currently. It allows annual contributions of up to 20 million won, and it was mentioned that the limit might expand to 40 million won depending on the introduction of new products in the future. The core of the ISA lies in 'separate taxation.' Although there are differences depending on the type of account, it provides tax-free benefits for interest and dividend income ranging from 2 million to 4 million won per year. For income exceeding this, one can enjoy the effect of being excluded from comprehensive financial income taxation by paying a low separate tax rate of 9.9%. The presenter added, "It is good to fill the limit as much as possible while the system is in place."
Pension Savings and IRP offer strong tax credit benefits. Pension Savings allow for a tax credit of up to 6 million won per year, and when combined with IRP, one can receive benefits of up to 9 million won per year. In other words, if 6 million won is deducted from Pension Savings, the structure allows for an additional 3 million won to be deducted through IRP. Furthermore, there is a 'tax deferral' effect where taxes on investment returns are not paid immediately but are paid later as pension income tax at a low rate when receiving the pension after age 55, which can maximize the compounding effect.
Regarding the order of account utilization, strategies by age group were presented. It is recommended that the younger generation prioritize using the ISA, which allows for relatively free withdrawal of principal, while for those in their 40s and 50s nearing retirement, a strategy of avoiding the risk of comprehensive financial income taxation and withdrawing assets through Pension Savings or IRP with low pension income tax is effective. However, he advised that if retirement is not far off, it is better to manage primarily through Pension Savings or IRP to escape the fear of comprehensive financial income taxation.
IRP '30% Safe Asset' Regulation... Asset Allocation Possible via Mixed ETFs
When executing asset allocation strategies using tax-saving accounts, one must consider the regulations for each account. In particular, for IRP, there is a regulation that 30% of the total assets must be invested in safe assets, which may make it difficult to apply general asset allocation strategies (e.g., 75% stocks, 25% bonds, etc.) as they are.
As a way to solve this, the use of 'mixed ETFs' was suggested. By using mixed products that mix stocks and bonds in a certain ratio, one can achieve the effect of diversifying investments into stocks and bonds while having the product recognized as a safe asset. The video gave 'KODEX US Treasury Mixed' as an example. Since this product consists of 50% stocks and 50% US Treasuries, using it allows one to efficiently implement the 'Four-Part Investment Strategy' of allocating 25% to KOSPI and 25% to US Treasuries while complying with the 30% safe asset ratio regulation. He explained that this makes management at the level of the 'Five-Part Investment Strategy' possible.
However, not all products can be purchased in tax-saving accounts. Overseas listed ETFs such as the US REIT ETF 'VNQ' cannot be purchased directly in an ISA or pension account. The practical limitation that domestic overseas REIT products cannot fully follow the performance of the global VNQ was also mentioned. Therefore, such assets must use general securities accounts (such as CMA, etc.), and it was advised that a 'modified asset allocation strategy' is needed to manage by substituting with US stocks or Dow Jones dividend ETFs within tax-saving accounts.
The presenter recommended laying the foundation for long-term investment through the tax deferral effect of delaying taxes and tax-saving benefits, stating, "The difference in performance between using tax-saving accounts and using general accounts is much larger than you might think."
0Comments
Comments are currently disabled.