
"The customer didn't ask for it" excuse won't work... 20% penalty tax for failure to issue cash receipts
Self-employed individuals in mandatory cash receipt issuance industries face heavy penalty taxes and tax audits if they fail to issue receipts…
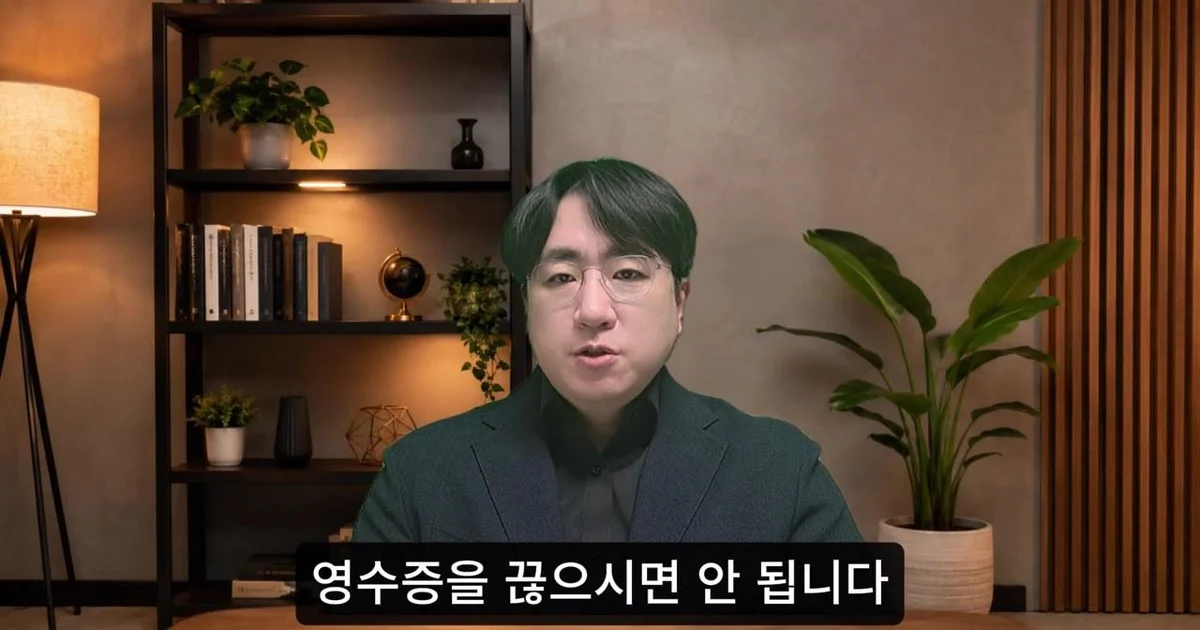
If a self-employed individual belonging to an industry subject to mandatory cash receipt issuance omits issuance on the grounds that "the customer did not request it" or "a discount was given including VAT," they may face massive penalty taxes and the risk of tax audits. According to a video from the YouTube channel 'Semujosa-neun Peonpeontaekseu | Guksecheong Josaguk Chulsin', the responsibility for the failure to issue cash receipts belongs entirely to the business owner.
"Must issue if 100,000 won or more"... Split payments also considered 'one transaction'
The list of industries subject to mandatory cash receipt issuance is trending toward expansion every year, including most industries closely related to daily life such as self-employed businesses, hospitals, clinics, oriental medicine clinics, Pilates studios, hair salons, academies, and private tutoring. The standard for mandatory issuance is when a cash transaction of 100,000 won or more (including VAT) occurs per case. The important point here is that regardless of whether the customer requests it, it must be voluntarily issued within 5 days.
The video also mentioned precautions regarding cases where the payment method is split. For example, if someone uses PT or yoga classes worth 1 million won and pays 950,000 won by card and the remaining 50,000 won in cash, they must issue a cash receipt based on the total transaction amount of 1 million won, rather than issuing a receipt only for the 50,000 won in cash. If this is missed and only a portion of the amount is issued or omitted, it can become subject to fines.
Targets for tax evasion reports are industry peers and former employees... Tracking possible up to 5 years ago
Failure to issue cash receipts does not simply end with the issue of fines. If caught through a report of tax evasion, the National Tax Service can retroactively investigate unissued details up to a maximum of 5 years ago. Since the reporting system is structured so that reporters can receive rewards, reports from competitors in the same industry, former instructors, or customers who left due to dissatisfaction with the service occur frequently.
In particular, the video explained that if a tax evasion report occurs, National Tax Service investigators may contact the business directly to inform them of the investigation progress. There are also cases where reporters certify the fact of reporting on online communities or SNS, placing significant psychological pressure on the business owner. If the fact of non-issuance is confirmed, a penalty tax equivalent to 20% of the unissued amount is imposed. Although the penalty tax rate, which was previously a maximum of 50%, has been adjusted downward, severe punishment still awaits.
For example, if the total sales for which cash receipts were not issued over 5 years amount to 500 million won, one might have to pay 100 million won in penalty taxes alone. If comprehensive income tax, local tax, and the four major social insurances for the unissued portions are subsequently imposed, it can deal a fatal blow to business operations.
Use of borrowed-name accounts and splitting businesses... Tax audit 'submission of explanatory materials' is scarier
The act of receiving payments through borrowed-name accounts of spouses or employees instead of business accounts to omit cash sales further exacerbates the problem. This goes beyond the issue of failing to issue cash receipts and leads to a separate tax issue called 'use of borrowed-name accounts,' creating a 'plus-plus' situation where penalty taxes and punishments are increased. Additionally, the act of installing multiple terminals or splitting businesses into several to disperse sales is also a matter requiring caution.
The video warned that receiving a 'notice for submission of explanatory materials' can be more difficult than receiving a tax audit notice. Since the submission of explanatory materials is a process of explaining past incorrect records, it is very difficult to respond if it contradicts the data already held by the National Tax Service. The presenter emphasized, "Even if the money received is used for rent, salaries, or reinvestment costs rather than the business owner taking all of it, the representative must bear all legal responsibility."
0Comments
Comments are currently disabled.