
Global Public Debt Nears 94% of GDP... '100% Debt Era' Predicted to Arrive by 2029
Global public debt is rising rapidly, with warnings that it will exceed global GDP within three years.
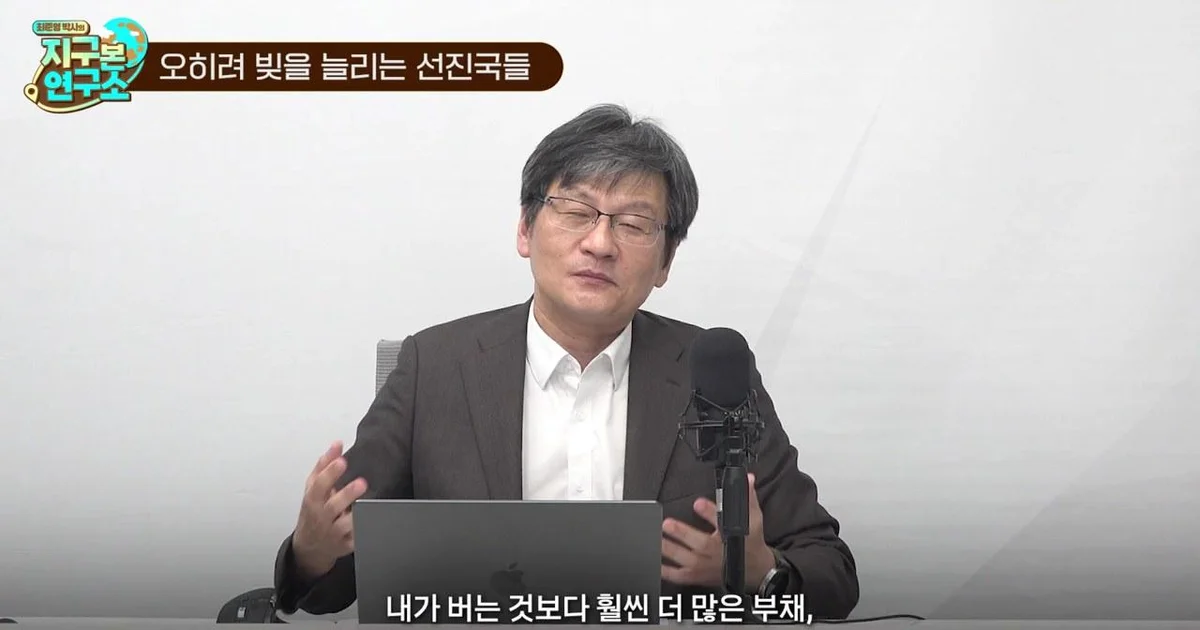
Global government public debt is increasing rapidly, growing uncertainty in the global economy. Warnings have emerged that the scale of global public debt will exceed the global GDP (Gross Domestic Product) within three years.
Global Debt Predicted to Surpass 100% of GDP by 2029
According to a video from Dr. Choi Jun-young's 'Globe Research Institute', IMF estimates show that as of 2025, global public debt has reached the level of 94% of GDP. In particular, for advanced nations, the debt-to-GDP ratio already exceeded 110% as of last year. This means advanced nations are carrying more debt than the value they produce annually.
The problem is the speed of debt increase. If the current trend continues, the point at which global public debt exceeds 100% of GDP is projected to be 2029. This phenomenon is occurring for the first time in about 80 years since 1946, immediately after World War II. At that time, debt surged to conduct the war, but the characteristic now is that debt is exploding even in a situation without war.
By country, the debt increase in China and the United States is prominent. China's debt-to-GDP ratio is currently at the 99% level but is expected to increase to 127% by 2031, while the United States is predicted to soar from the current 124% to 142% by 2031. The presenter expressed concern, stating, "If the two countries leading the world far exceed 100% of GDP, the world could become even stranger in the 2030s."
Surging Interest Burden... The United States Could Pay Half Its Taxes in Interest
The expansion of debt scale leads directly to a surge in interest costs. The proportion of interest payments relative to global GDP increased from approximately 2% in 2021 to 3% as of 2025. This means the interest burden has increased by 50% in just five years.
In particular, the pressure exerted on the United States economy is significant. The United States is currently experiencing a continuous fiscal deficit of about 7–8% of its GDP. The presenter explained, "If the current pace is maintained and we reach 2029, the United States might have to pay approximately 2.7 trillion dollars in interest every year." This is nearly half the amount of taxes the United States collects in one year (approximately 5 trillion dollars). The analysis suggests that even the United States, with its powerful economic strength, could fall into a dilemma of debt repayment and interest payments.
Looking at the interest burden ratio by country, the United States is nearing about 5% of GDP, followed by Italy (4%), Canada (3.5%), and the United Kingdom (3.3%). The average for middle-range OECD countries is slightly less than about 3.5%. On the other hand, France and Japan show relatively lower immediate interest burdens due to the influence of bonds issued during past low-interest rate periods. Germany maintains a relatively low level thanks to its traditional balanced budget stance.
Vicious Cycle of Decreasing Central Bank Demand and Rising Government Bond Yields
As debt increases, the volume of government bond issuance increases, and when supply becomes abundant, government bond prices fall and interest rates rise. The global bond market is currently undergoing such structural changes. In the past, central banks of major countries served as key demand sources for government bonds and supported the market, but their stance has been changing since 2024.
The presenter analyzed, "As central banks of major and emerging countries begin to lower interest rates, they are reducing their holdings of government bonds," adding, "As the perception spreads that holding more government bonds is a loss, demand has decreased significantly." Consequently, in order to issue long-term bonds, a higher premium must be added. In fact, the term premium is currently formed more than 1 percentage point higher compared to 2019.
Recently, a phenomenon where the 'yield spread'—the difference in yields between government bonds and corporate bonds—disappears has also been observed in the market. Since July of this year, statistics have appeared showing that government bonds have lower yields than corporate bonds, and the perception among investors that "government bonds are not as good as corporate bonds" is spreading. Furthermore, evaluations suggest that the '5% era' has definitely opened, with the U.S. 10-year Treasury yield hovering around 5%. In fact, on September 14, 2026, it exceeded 5% for the first time in 20 years.
Other factors shrinking the demand for government bonds include the large-scale AI investments by Big Tech companies and changes in the management methods of retirement pensions. As Big Tech companies absorb massive funds for AI-related investments, a competition is occurring where funds in the bond market become scarce, causing interest rates to rise. Additionally, as retirement pensions shift from the past Defined Benefit (DB) type to the Defined Contribution (DC) type, which increases the proportion of stocks, the reduction of the major demand group that used to buy long-term government bonds was also cited as a cause for the shrinking demand for government bonds.
The presenter pointed out, "Most countries are not showing the will to solve the debt problem, choosing policies focused on economic growth rather than austerity or balanced budget management to reduce debt." The core of the problem is that to reduce debt, important efforts are needed to reduce borrowing and pay back more than usual, but many countries are currently distancing themselves from such efforts.
0Comments
Comments are currently disabled.