
"Gold Prices Overvalued by 30%"... Professor Kim Young-ik Warns to Prepare for Short-term Correction Amid Mid-to-Long-term Upward Trend
Professor Kim Young-ik analyzes that while gold has high potential for mid-to-long-term growth…
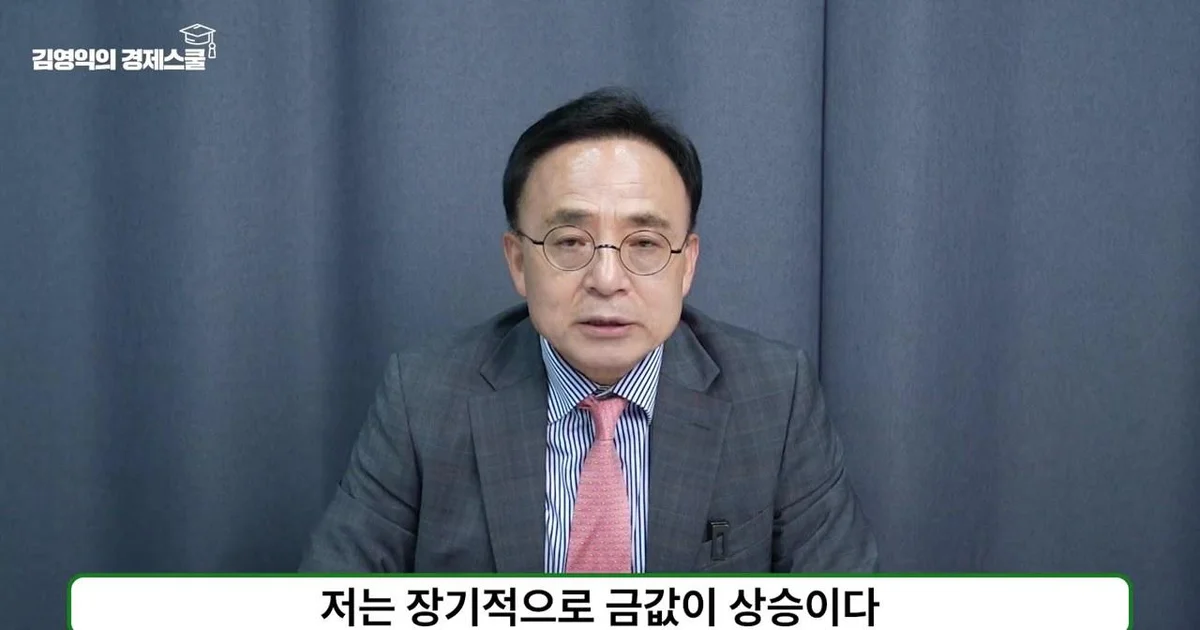
As gold prices exhibit volatility with recent rapid surges and plunges, an analysis has emerged suggesting that while the possibility of a mid-to-long-term rise in gold is high, a price correction is necessary in the short term. Although gold has the limitation of being an asset that does not provide interest or dividends, the advice is to maintain a certain proportion in terms of asset allocation.
"Gold Prices in an Overvalued Zone Based on Economic Variables"
Regarding recent gold price movements, discussions in the market are divided on whether it is a trend-driven rise or a temporary rebound. According to the 'Kim Young-ik's Economics School' video, the current gold price is in a state of being overvalued by approximately 30% when evaluated against major economic indicators such as the United States Consumer Price Index (CPI), the Dollar Index, and the U.S. 10-year Treasury yield.
The presenter diagnosed that "in the short term, a correction phase is needed rather than the possibility of a surge." In particular, he explained that since the level of overvaluation relative to economic variables reached 60% at the end of last year and early this year, it would have been appropriate for investors holding a 10% gold allocation at that time to reduce it to around 5%. However, he predicted that the recent rebound is not a point where it can surge by breaking through previous highs, and it may undergo additional corrections.
Inflation, Dollar, Interest Rates... The 3 Core Drivers Moving Gold Prices
The most influential factor among the key factors determining gold prices is 'inflation.' According to the video analysis, when the United States Consumer Price Index rises by 1%, the gold price rises by approximately 3.7%, showing that gold reacts most sensitively as an inflation hedge. Furthermore, when the Dollar Index falls by 1%, the gold price rises by 1.4%, and a fall in U.S. interest rates also acts as a factor for rising gold prices.
From a mid-to-long-term perspective, the outlook for a weak dollar supports the rise in gold prices. Pointing out the massive government debt and external debt issues of the United States, the presenter analyzed, "In the process of resolving the internal and external imbalances of the United States, the Dollar Index is bound to fall in the mid-to-long term." Additionally, citing the IMF's forecast that the United States' share of global GDP will shrink by 2031, he predicted that the possibility of a weak dollar continuing for about the next 5 years is high. The logic is that if a fall in U.S. interest rates due to an economic slowdown is added to this, gold prices will inevitably face upward pressure.
In terms of supply and demand, the gold buying trend of central banks is an important variable. Recently, the world's central banks have been diversifying their foreign exchange reserve proportions from the dollar to the euro, yen, yuan, etc., and it is particularly noteworthy that China is trending toward reducing its holdings of U.S. Treasuries and increasing its gold proportion. China's U.S. Treasury holdings decreased by more than half, from 1.27 trillion dollars at the end of 2013 to around 618 billion dollars in July this year. The presenter explained, "While the gold proportion in the foreign exchange of major European countries is over 70%, China is only at the 8.8% level, so there is a high possibility that China will reduce U.S. Treasuries and continue to buy gold."
Why Gold, the "Hen That Doesn't Lay Eggs," is Recommended for a 10% Asset Allocation
Gold is a very attractive asset in the long term. Looking at the monthly average growth rate for the 26-year period from 2000 to 2025, gold recorded the highest return of 10.8%, surpassing the KOSPI (8.0%, excluding dividends) and the national average apartment price growth rate (4.6%). Among commodities, the upward trend was most distinct in the order of gold, silver, and copper.
Nevertheless, the reason the presenter recommends holding only about 10% of total financial assets in gold is due to the characteristics of gold. Quoting Warren Buffett and comparing gold to a "hen that cannot lay eggs," the presenter pointed out, "Stocks provide dividends even when stock prices fall, and bonds provide interest, but gold itself does not generate any cash flow." Considering that if gold prices enter a downward phase, the correction period could extend up to 5 years, the explanation is that proper asset allocation is needed rather than concentrating excessively on gold, which has no cash flow.
Gold investment methods include the KRX Gold Market, gold ETFs, gold accounts (gold banking), and purchasing gold bars. The presenter mentioned utilizing gold ETFs, which allow for easy trading like individual stocks, and advised choosing various methods according to one's financial situation.
0Comments
Comments are currently disabled.