
Gift tax may apply if 10-year cumulative parental gifts exceed 50 million won
Gift tax is determined by the total amount received from donors over a 10-year period rather than a single transaction, meaning a 10 million won gift could be taxable if previous gifts exceed deduction limits.
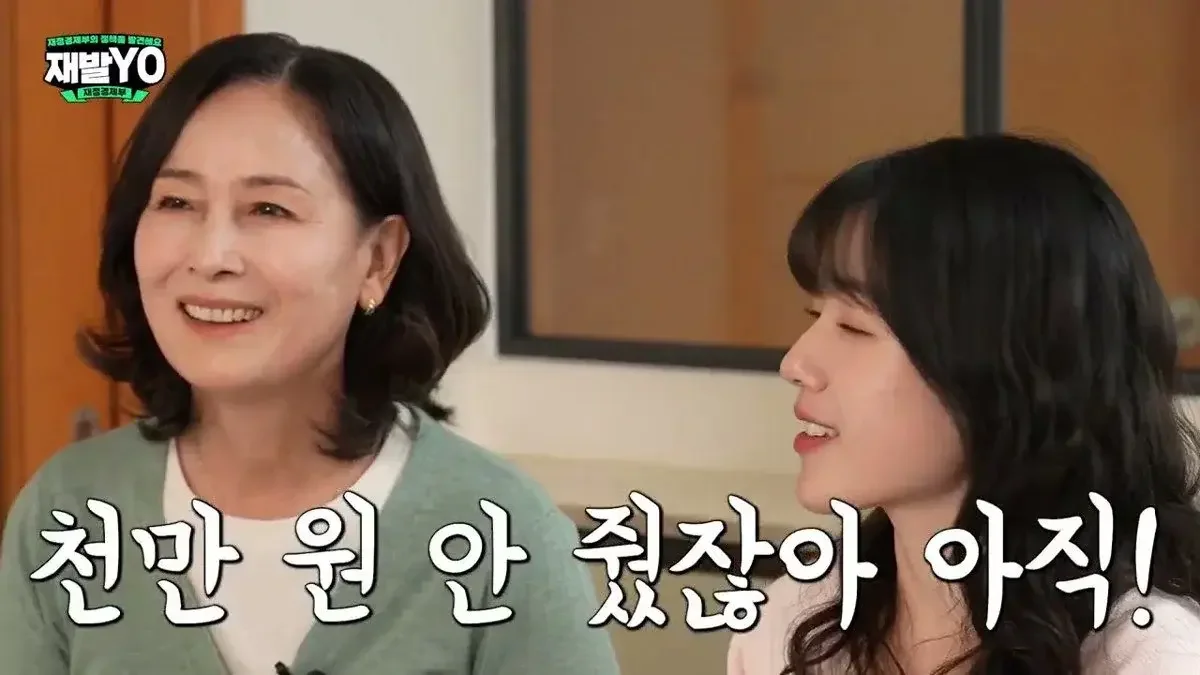
The Ministry of Finance and Economy warned that receiving 10 million won from a mother could trigger gift tax if a child has already received 45 million won from a father within the last 10 years, as the 50 million won deduction limit applies to the combined total from both parents.
When transferring cash from parents to children, a small amount does not necessarily mean one can ignore tax concerns. This is because gift tax is determined not just by the amount transferred at once, but by aggregating all previous gift history.
In a video released by the Ministry of Finance and Economy, a mother and daughter addressed gift tax issues within a family. The video examines whether gift tax applies in a scenario where a daughter preparing for employment requests 10 million won from her mother as investment funds for her future.
The key is who the gift is from and the 50 million won 10-year total
The first things to check in a family gift are "who the money is from" and "the total amount received over the recent 10 years." Under current tax law, when parents gift money to a child, a gift property deduction of up to 50 million won is applied over a 10-year period, resulting in no tax being incurred.
In the case presented in the video, if the daughter intends to receive 10 million won from her mother but has already received 45 million won from her father within the past 10 years, the situation changes. Adding the 10 million won from the mother brings the total to 55 million won, exceeding the 50 million won deduction limit. In this case, gift tax may be imposed on the excess amount.
One aspect many people overlook is the identity of the donor. Because parents are often considered the same person under tax law and are subject to aggregated taxation, money received from a mother and money given by a father should not be calculated separately. To ensure accurate tax calculation, the 10-year periodic deduction limit must be managed by aggregating both parents.
Gift property deduction limits and the importance of reporting
A key variable in calculating gift tax is how much of the gift property deduction limit remains. The deduction limit varies depending on the age of the recipient and their relationship with the donor. While the standard is 50 million won for an adult child receiving from a parent, the limit drops to 20 million won for a minor child.
Furthermore, gift tax is not finalized simply by the act of exchanging money; it must be verified through reporting procedures. The video mentions that records are left when cash is exchanged between family members, suggesting that unplanned gifts can lead to unexpected tax burdens.
Ultimately, when moving funds within a family, one must check ▲who the donor is, ▲the cumulative gift amount within the last 10 years, and ▲the remaining deduction limit. If large sums are exchanged without these checks, there is a possibility of being subject to gift tax collection by tax authorities later.
Source: original video (YouTube)
0Comments
Comments are currently disabled.