
"Best in Korea" Tax Accountant Exaggerated Advertising Prohibited... Must Distinguish Between VAT Preliminary Return and Preliminary Notice
The National Tax Service has announced new regulations to prohibit tax accountants and other tax agents from using exaggerated claims like "best in Korea" without objective evidence. Additionally, the service provided guidance on distinguishing between the "preliminary return" and "preliminary notice" systems for Value Added Tax (VAT) in October.
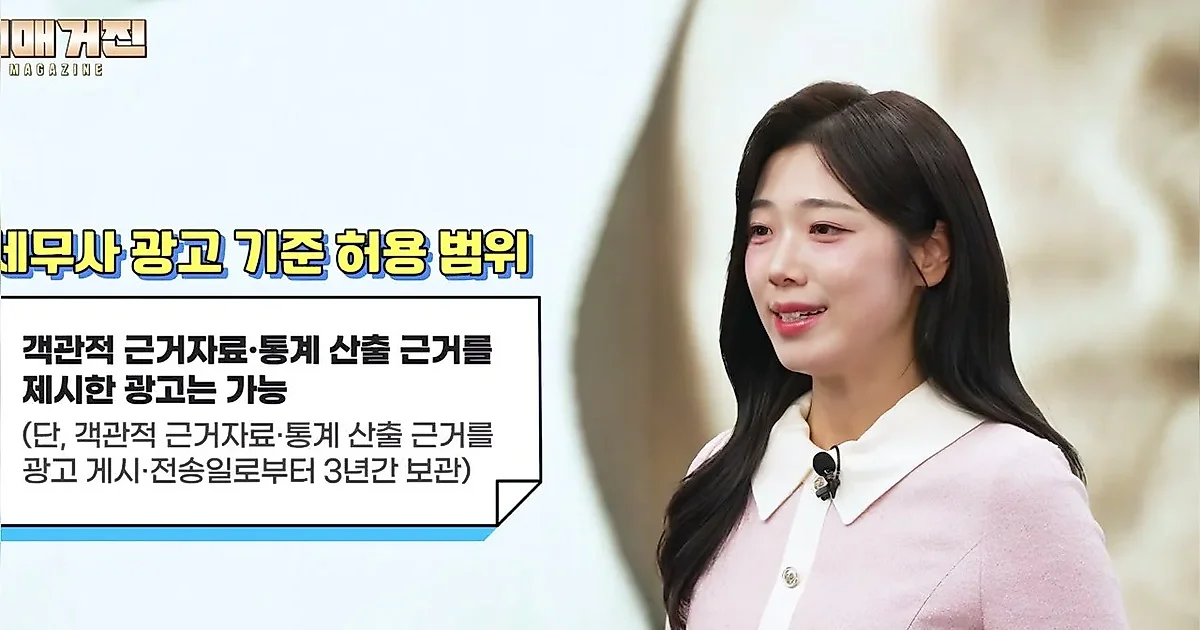
Moving forward, tax accountant advertisements that emphasize superiority without objective evidence, such as "best in Korea" or "No. 1 refund rate," will be restricted. The National Tax Service announced that it has prepared a draft of the "Regulations on Advertising Prohibited for Tax Accountants and Others" to prevent taxpayers from being misled by exaggerated or misleading advertisements.
Prohibition of Unfounded "Best" or "No. 1" Advertisements... Strengthening Advertising Standards for Tax Agents
According to the National Tax Service video, this draft notice applies equally not only to tax accountants but also to lawyers, certified public accountants, and foreign tax advisors who are registered for tax agency services. In particular, the same standards apply not only to advertisements produced directly by the individual but also to advertising materials posted through advertising agencies or online platforms.
Major prohibited items include: ▲ advertisements that directly compare fees with those of other tax accountants ▲ advertisements that promise the provision of money, goods, or economic benefits to induce engagement ▲ advertisements that emphasize superiority, such as "best in Korea" or "best in the industry," without objective evidence. Furthermore, advertisements that promote business performance, such as refund rates, tax savings rates, or success rates, without a basis for calculation, are also subject to prohibition.
However, not all advertisements are blocked. It is possible to disclose one's own fees based on facts, and if sufficient objective data and calculation bases for statistics can be presented, one can advertise business performance results such as refund rates or tax savings rates. The National Tax Service plans to establish a reporting channel on its website and strengthen inspections and crackdowns on violating advertisements.
October VAT: Checking the Target for "Preliminary Return" and "Preliminary Notice" is Essential
Meanwhile, in conjunction with the October Value Added Tax (VAT) preliminary return and payment period, caution was urged regarding the difference between "preliminary return" and "preliminary notice." These two systems are distinguished by whether a business operator calculates and reports their performance directly or pays the tax amount calculated by the National Tax Service.
Generally, corporate businesses are subject to "preliminary return," where they directly report based on business performance from July to September. On the other hand, individual general taxpayers and small-scale corporate businesses with a total supply value of less than 150 million won in the previous taxable period are subject to "preliminary notice," where the National Tax Service calculates and informs them of 50% of the tax amount paid in the previous taxable period.
However, not all those subject to preliminary notice will have a notice sent to them. Those who had no tax amount paid in the previous taxable period, those who started a new business during that period, or those who transitioned from simplified taxpayers to general taxpayers are excluded from the preliminary notice. Additionally, if the preliminary notice amount is less than 500,000 won, it will not be notified, and it can be reported and paid together during the next final return.
There are also exception regulations where even those subject to preliminary notice can choose to file a preliminary return directly depending on their business situation. In cases where the supply value or tax amount paid during the preliminary return period has decreased to less than one-third of the previous taxable period due to business suspension or poor business performance, or in cases where early refunds must be received due to exports or facility investment, a direct preliminary return can be made. In such cases, the existing preliminary notice is canceled.
An official from the National Tax Service emphasized that those who receive a preliminary notice must check the payment deadline. This is because if the notified tax amount is not paid and is delayed until the final return period, a late payment penalty may be imposed.
0Comments
Comments are currently disabled.