
Corporate Car Lease, Rent, or Direct Purchase: Tax Savings Ratios are Similar Under Specific Conditions
While there are debates over whether leasing or renting is more tax-efficient for corporations, the final tax savings ratio remains essentially similar under specific conditions due to the way expenses are processed under tax law.
The biggest dilemma for corporate representatives when preparing a vehicle is whether to purchase it directly, lease it, or use long-term rental. Some argue that leasing is advantageous for tax reduction or that renting is more effective for expense processing. However, if one examines the expense processing structure under tax law under specific conditions, the final tax savings ratio according to the method may not essentially differ.
Business Passenger Vehicle Expense Processing: 'Business Use Ratio' is Key
Under tax law, general passenger cars are classified as 'business passenger vehicles' and are subject to separate expense processing regulations. General passenger cars such as the Genesis G80 or GRANDEUR follow separate expense processing regulations, while light cars or cargo vehicles may be applied differently from these regulations. Not all vehicle-related costs (purchase price, lease/rent fees, insurance, automobile tax, fuel, tolls, etc.) are recognized; the core lies in how much the vehicle was 'used for business.'
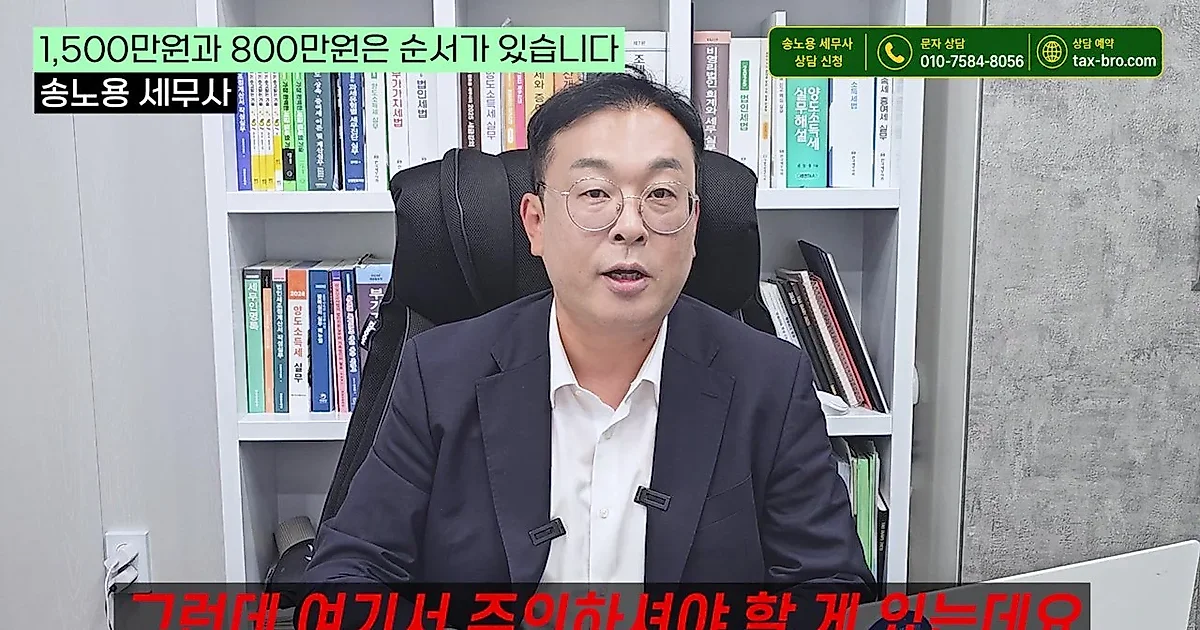
Tax law calculates the ratio of business use among the total costs incurred for the vehicle. If a driving log is maintained, expenses can be recognized according to the business use ratio of the total mileage. If a driving log is not maintained, if the annual vehicle-related costs are 15 million won or less, the business use ratio is considered to be 100% for expense recognition. If the annual vehicle-related costs exceed 15 million won, the business use ratio is calculated by dividing 15 million won by the total vehicle costs. However, caution is required as this limit decreases to 5 million won and 4 million won respectively for entities subject to faithful reporting, such as real estate rental corporations.
Additionally, for the 'depreciation (or the amount equivalent to depreciation among lease/rent fees)' corresponding to the car price among vehicle-related costs, a separate annual limit of 8 million won applies. For example, if the calculated depreciation is 10 million won, only up to 8 million won is recognized as an expense for the current year, and the remaining 2 million won is excluded. However, these non-deducted amounts do not disappear but are carried over to subsequent years, creating a structure where they can eventually all be recognized as expenses.
If a vehicle under a corporate name is actually used for personal purposes by a spouse or child, it can become a problem. If a portion is used privately, not only are there restrictions on expense processing, but in the case of a corporation, if the representative uses it privately, a bonus disposition may be issued to the representative. If a vehicle is used almost exclusively for private use, it goes beyond a simple matter of expense recognition and the vehicle itself may be considered an 'asset unrelated to business.' Furthermore, even if a general passenger car is used 100% for business, one cannot in principle receive a value-added tax input tax credit for the vehicle purchase price or maintenance costs.
Green License Plates and Employee-Only Insurance: Essential Checkpoints
When operating a corporate vehicle, the variables that must be checked are the 'green license plate' and 'employee-only automobile insurance.' A corporate business passenger vehicle with an acquisition value of 80 million won or more must attach a green license plate. The 80 million won standard is based on the 'factory price on the automobile registration certificate' excluding value-added tax, not the actual payment amount. Even if the actual payment amount is less than 80 million won due to dealer discounts, etc., if the factory price reflected in the vehicle manufacturing certificate and registration data exceeds the standard, the license plate must be attached. If a target vehicle does not attach a green license plate, the business use amount may be considered 0 won and expense processing may be denied, and depending on the case, income tax may be imposed as the vehicle user may be considered to have used the vehicle for free. Target vehicles may also include leased vehicles contracted by the corporation and corporate rental cars leased for one year or more.
Insurance is also important. Corporate vehicles must be enrolled in 'employee-only automobile insurance.' If a general insurance policy that includes family members, etc., is signed, all costs for that vehicle will not be recognized as business expenses for tax purposes. In the case of individual business owners, if they are obligated to keep double-entry books, there is no obligation to sign up for insurance for one vehicle, but from the second vehicle onwards, they must sign up for employee-only insurance to receive expense recognition.
Genesis G80 Case Comparison: Differences in the Timing of Expense Processing
Comparing direct purchase, operating lease, and long-term rental by setting conditions for operating a Genesis G80 (2.5 Turbo) model for 5 years shows that the patterns of expense processing differ depending on the method. For comparison, the vehicle price is based on a cash price of 59 million won (approximately 63 million won including acquisition and registration tax), and lease and rental are set with 0 won initial cost, 60 months, 20,000 km per year, and a return at maturity condition. Assuming all tax law requirements are met and the business use ratio is 100%, the 'corporate tax savings ratio relative to total expenditure' for all three methods converges to around 20%.
This is because, regardless of which method is chosen, taxes are reduced by the same tax rate for the expenses incurred. However, the 'timing of expense processing' may differ depending on the method. In the case of the video, because the monthly rental fee for long-term rental does not hit the depreciation limit (8 million won), it appears that rental processes expenses most quickly during the operating period. On the other hand, direct purchase or lease gets pushed back in expense processing because they hit the annual 8 million won limit. However, since the delayed expenses are eventually recognized later, there is no difference in terms of the total final tax savings amount.
In conclusion, the statement that leasing is advantageous for tax reduction can be interpreted to mean that it may be advantageous in terms of cash flow because expense processing occurs more quickly. However, if the lease fee itself is higher than a direct purchase, even if the tax savings amount is large, it might actually be disadvantageous when considering the tax savings ratio relative to the actual expenses incurred. Additionally, decisions should be made by comprehensively considering the cost structure of each method, such as the fact that a value-added tax payment obligation may arise when selling the vehicle in the case of a direct purchase.
0Comments
Comments are currently disabled.