
"Like dividing shareholders into first-class and second-class citizens"... Controversy over '50%+1 share' Mandatory Tender Offer System
Criticism has been raised regarding the imbalance in the design of the 'Mandatory Tender Offer System' bill, which aims to distribute management control premiums to general shareholders when control of a listed company changes. The controversy stems from the mandatory purchase ratio being lowered to '50%+1 share' instead of the originally discussed '100% purchase,' combined with a 'preemptive purchase' clause that prioritizes the controlling shareholder's stake.
Criticism has been raised regarding the imbalance in the design of the 'Mandatory Tender Offer System' bill, which aims to distribute management control premiums to general shareholders when control of a listed company changes. This is because the bill, which passed the National Assembly Political Affairs Committee, has had its mandatory purchase ratio lowered to '50%+1 share' instead of the originally discussed '100% purchase,' and includes a 'preemptive purchase' clause that prioritizes the controlling shareholder's stake.
Combination of '50%+1 share' and 'Preemptive Purchase'... Concerns over discrimination among shareholders
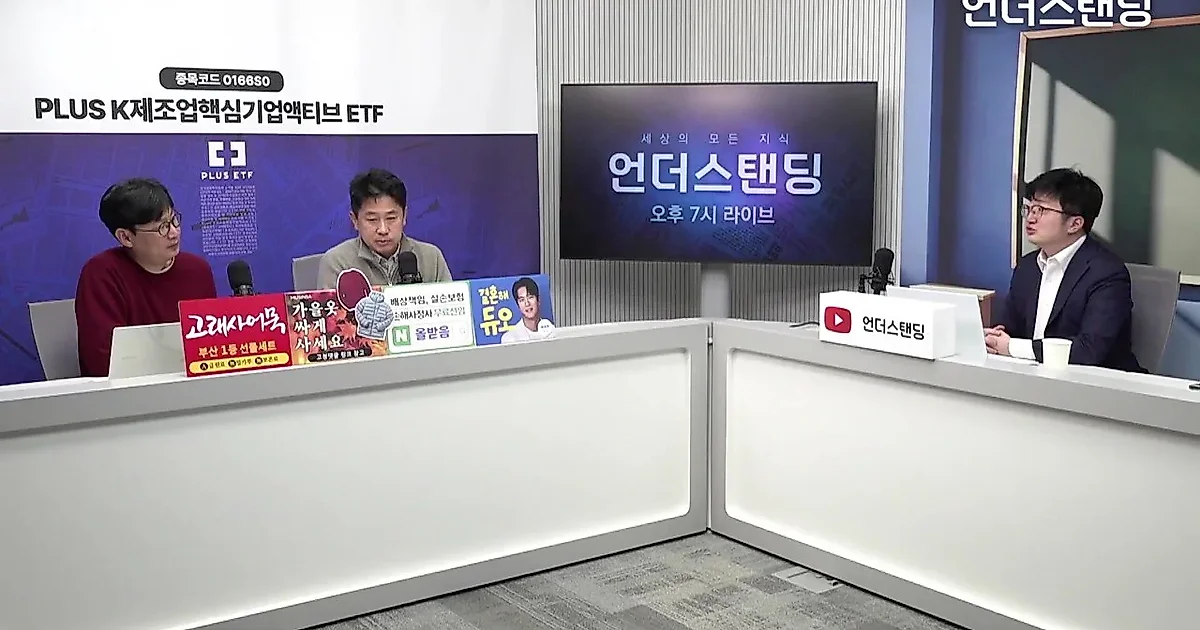
Lee Chang-hwan, CEO of Align Partners, appearing on the YouTube channel 'Understanding,' pointed out the structure of the current mandatory tender offer bill, explaining that it could effectively result in dividing shareholders into 'first-class citizens' and 'second-class citizens.' According to the explanation in the video, the current bill adopts a method where 'preemptive purchase' is allowed for the controlling shareholder's stake first, and then general shareholders participate in the remaining volume.
Using a company where the controlling shareholder holds a 40% stake as an example, Lee mentioned that if the controlling shareholder conducts a preemptive purchase to fill the 50%+1 share, a situation arises where the remaining general shareholders must compete for the very small amount of remaining volume. This is pointed out to be different from the 'pro-rata purchase' method used by Japan's ZOZO, where controlling and general shareholders sell at the same ratio to share the management premium, or the method that South Korea introduced in 1997. Lee raised the question that if the initial goal was a 50% purchase, there would have been no reason for a preemptive purchase clause to exist, suggesting that the structure may have become unintentionally tangled during the process of revising the 100% purchase plan to 50%.
43% of companies have controlling shareholder stakes of 50% or more... Benefits for minority shareholders are limited
Specific statistical figures regarding the effectiveness of the bill were also presented. According to the results of Lee's analysis of 35 management control transactions of listed companies (based on a market capitalization of 300 billion won or more) that occurred since 2015, 15 of those transactions, accounting for about 43%, were cases where the controlling shareholder's stake was already 50% or more. In such cases, since the controlling shareholder only needs to sell their own stake while receiving the premium through the preemptive purchase clause, the mandatory tender offer system effectively fails to function in guaranteeing a share for general shareholders.
Furthermore, a survey of 200 KOSPI-listed companies showed that 93% of the surveyed companies have controlling shareholders, and their average stake was 44%. Citing the tendency that companies with higher controlling shareholder stakes tend to have lower PBR (Price-to-Book Ratio), which represents corporate value, Lee mentioned the risk of the value of the remaining shares decreasing after the controlling shareholder sells part of their stake and the possibility of infringing on the rights of general shareholders. In the actual surveyed data, the average PBR for companies with a controlling shareholder stake of less than 30% was 2.64 times, whereas the average PBR for companies with a controlling shareholder stake of 50% or more was 1.31 times.
Plenary session processing postponed... Necessity for supplementing the legislative process raised
Currently, the processing of the bill in the plenary session of the National Assembly is postponed, and whether it will be revised in the future remains uncertain. In the video, the core issue discussed was that this legislation could conflict with the recent trend of Commercial Act amendments aimed at treating all shareholders equally and the discussions regarding the duty of loyalty to shareholders. Lee emphasized that even if this bill started with the good intention of protecting minority shareholders, it is designed in a structure advantageous to controlling shareholders, which could directly affect individual retail investors, and expressed the need for institutional supplementation.
0Comments
Comments are currently disabled.