
Gold and silver could rebound if Treasury yields decline
Commodities including gold and silver are expected to see a strong rebound if inflation slows and Treasury yields turn downward, according to market analysis.
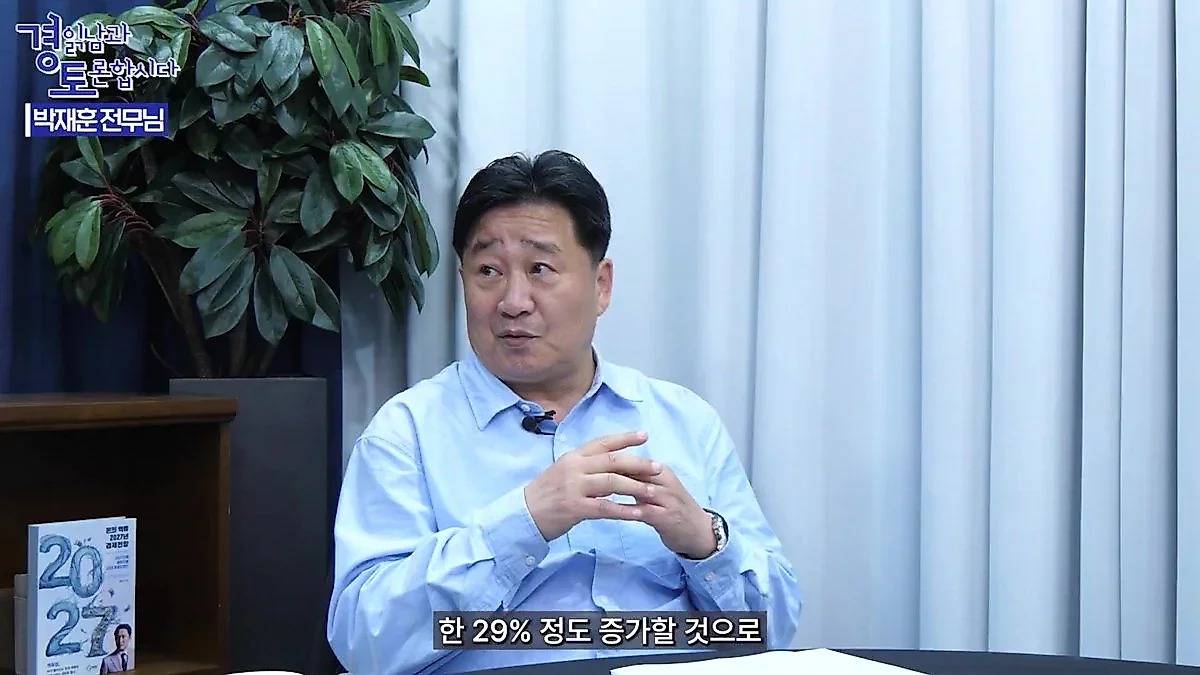
Gold and silver prices may see a strong rebound if inflationary pressures moderate and interest rates pivot downward, according to Park Jae-hun of Wells Guide. While central banks including China purchased over 1,000 tons of gold between January and August this year, high Treasury yields continue to pressure asset markets.
As high U.S. Treasury yields continue to pressure asset markets, projections have emerged regarding which assets will benefit most if interest rates eventually pivot downward. Analysis suggests that if inflationary pressures moderate, the commodities market, including gold and silver, could see a strong rebound.
In a discussion hosted by The Man Who Explains the Economy (Kim Kwang-seok TV), Park Jae-hun, an executive at Wells Guide, diagnosed the current high-interest-rate environment and discussed asset allocation strategies based on future market trends. Park identified inflationary pressure as the core factor maintaining high Treasury yields. He analyzed that pressures on both the supply and demand sides—driven by rising oil prices and increased investment spending by hyperscale companies in the U.S.—are preventing interest rates from falling. He added that the Fed's stance of continuing to raise rates is also influencing market sentiment.
Commodities like gold and silver could see 'strong rebound' if inflation slows
Park predicted that while inflation may not drop sharply, it will moderate gradually due to its "sticky" nature. "If the factors driving the rise are broken, the standard for rising interest rates will naturally break as well," he said, forecasting that a pivot to lower interest rates would have a very positive impact on investment sentiment. He noted that the Treasury market would be immediately affected once the decline in interest rates begins.
In particular, he emphasized the need to watch gold and silver. Citing real interest rates, dollar flows, and central bank buying as the three key factors determining gold prices, Park explained, "If inflation expectations decrease and real interest rates fall, the opportunity cost of holding gold will disappear, making it highly likely that gold prices will rise." He also noted that major central banks, including China, have maintained a buying trend, purchasing more than 1,000 tons of gold between January and August this year.
Regarding the U.S. stock market, he expected a steady trend based on corporate earnings. Park predicted that the earnings per share (EPS) of S&P 500 companies in the third quarter would increase by approximately 29% compared to the same period last year. Assuming the current EPS is 400, a 29% increase would reach approximately 412; applying an average price-to-earnings (PER) ratio of 19 to 20, he presented a specific scenario where the S&P 500 index could rise to the 8,700 to 9,000 level. He analyzed that these expectations could be reflected in stock prices in conjunction with the corporate earnings season starting from the third week of March.
Korean market variables include 'investor sentiment' and 'rotation of leading stocks'
In contrast to Park's optimistic outlook for the U.S. market, a cautious view was raised regarding the Korean market. While Professor Kim noted that the earnings of Korean companies, led by Samsung Electronics and SK hynix, are beyond doubt, he pointed out that investor sentiment is a separate issue.
"The flow of the real economy is like the will of the people, but investor sentiment is different," Kim explained. "Korean investors have become very cautious after experiencing a major market downturn, and because they doubt whether they can recover to previous highs, there is a strong tendency to realize profits during rebounds." He also mentioned the possibility of a "rotation of leading stocks," where the trend concentrated in specific sectors, as seen previously with NVIDIA, might change. He attributed the market being trapped in a box range in 2026 to the phenomenon where investor sentiment fails to concentrate on specific leading stocks.
Conversely, the U.S. market was presented as having a different structure from the Korean market, as the Nasdaq encompasses various sectors, allowing it to hit new highs daily even if leading stocks rotate. The analysis suggested that the U.S. has the strength to lead the market through a rotation of leading stocks into sectors other than semiconductors, even under high Treasury yields.
Resolution of geopolitical uncertainty as an additional driver for gold rebound
Regarding the direction of gold prices, Kim proposed "geopolitical uncertainty" as an additional variable to the three factors presented by Park (real interest rates, the dollar, and central bank buying). While gold prices are currently being suppressed by interest rates, he analyzed that the point at which geopolitical risks are resolved could serve as an inflection point.
"The economy is always a realm of comparison," Kim added. "If geopolitical uncertainties, such as the war in the Middle East, are resolved after the U.S. midterm elections, this could be a factor that prevents gold prices from rebounding strongly; conversely, the key will be how the character of gold as a safe-haven asset changes during the process of resolving uncertainty." He noted that the current high interest rate environment limits preference for gold as a safe-haven asset and continued the discussion by stating that gold's movements must be closely watched given unpredictable variables, such as the possibility of challenges to results following the midterm elections.
Source: original video (YouTube)
0Comments
Comments are currently disabled.