
Principal and interest may be invalidated for illegal high-interest lending
Victims of illegal private financing that exceeds the legal maximum interest rate may find both their principal and interest invalidated under certain extreme conditions.
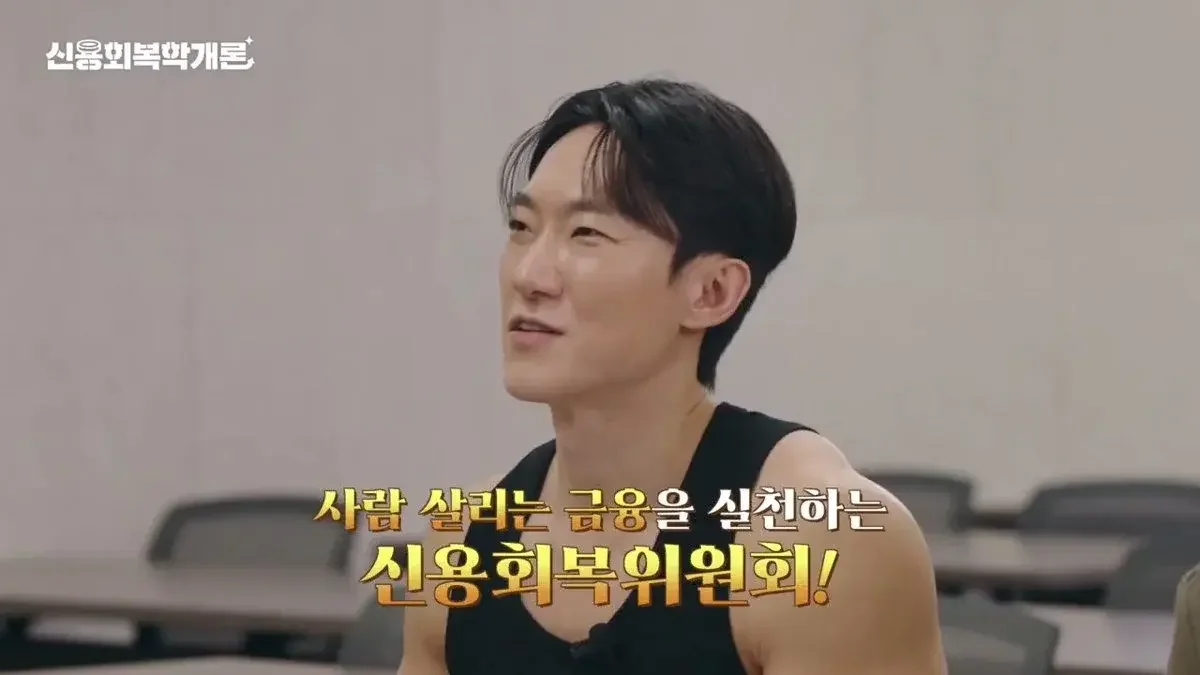
Under certain conditions, borrowers may not have to repay both principal and interest if illegal lending exceeds the 20% annual legal maximum rate. The Credit Counseling and Recovery Service warned that extreme cases, such as interest rates reaching 6,000% per year, require victims to seek professional assistance to handle administrative and judicial responses.
It has been revealed that if victims suffer from illegal private financing that exceeds the legal maximum interest rate, not only the excess interest but, depending on the circumstances, the entire principal and interest may be invalidated. Financial consumers must accurately recognize the types of illegal private financing and respond by seeking help from professional institutions when damage occurs.
'Principal and Interest Invalidation' applied when exceeding 20% legal maximum rate
According to the 'Introduction to Credit Recovery' video released by the Credit Counseling and Recovery Service, the legal maximum interest rate permitted under the Interest Limitation Act in Korea is 20% per year. High-interest lending that exceeds this is clearly illegal. In particular, when the legal maximum interest rate is violated under the Money Lending Business Act, it is not just the excess interest portion that becomes invalid; under certain conditions, situations may arise where neither the principal nor the interest needs to be repaid.
Specifically, while there are cases where only the excess interest exceeding the 20% legal maximum is invalidated, in extreme illegal high-interest situations, such as when interest rates exceed 60%, invalidation regulations may apply where both principal and interest do not have to be repaid. However, this is a legal mechanism intended to punish illegal moneylenders, and it is separate from the act of a debtor intentionally refusing to repay borrowed money, involving the issue of restoration to the original state according to legal procedures.
Illegal private financing is largely classified into four types: ▲ high-interest lending exceeding the legal maximum rate, ▲ unregistered lending by non-registered lenders, ▲ illegal debt collection accompanied by threats or verbal abuse, and ▲ loan fraud that induces scams using loans as bait or utilizes fraudulent bank accounts. In particular, there is a growing need for caution as cases are increasing where individuals are exposed to smishing crimes and have their mobile phone personal information stolen while searching for keywords such as 'small loans' or 'emergency loans' online.
From students suffering 6,000% annual interest to the reality of illegal private financing
Damage from illegal private financing appears across all age groups, but it is reported to be particularly serious among students who are vulnerable to information. Through counseling cases, an official from the Credit Counseling and Recovery Service disclosed a case of a student who borrowed funds through online games and was subjected to a murderous interest rate reaching 6,000% per year.
Such victims often suffer from secondary damage and psychological terror, such as their mobile phone personal information being stolen leading to contacts being made to acquaintances, or posts being uploaded that mock the debtor. Because illegal private financing leads to collection accompanied by threats and coercion beyond simple monetary problems, there are clear limits to victims resolving the issue on their own.
Use '1375' and 'Credit Counseling and Recovery Service' when damage occurs
If one has suffered damage from illegal private financing or is being threatened, they must immediately seek help from professional institutions. If a victim visits with evidence remaining on their mobile phone, the Credit Counseling and Recovery Service supports administrative and judicial responses, such as organizing the data and delivering it to the Financial Supervisory Service and the Korean National Police Agency. Additionally, it performs the role of connecting victims so they can receive legal assistance through the Korea Legal Aid Corporation.
When financial support is needed, it is safe to use the Korea Inclusive Financy Agency or the Credit Counseling and Recovery Service. The Korea Inclusive Financy Agency supports small-scale policy fund loans, while the Credit Counseling and Recovery Service is in charge of debt adjustment work. To use institutional finance instead of illegal private financing, one must verify if the lender is a registered moneylender, and it is recommended to consult through the Korea Inclusive Financy Agency or the Credit Counseling and Recovery Service whenever possible.
An official from the Credit Counseling and Recovery Service emphasized, "The integrated consultation service (1375) of the Credit Counseling and Recovery Service and the Korea Inclusive Financy Agency serves as a safety net in the financial sector. When in difficulty, one should not hide like a criminal but resolve the problem through professional institutions."
Source: original video (YouTube)
0Comments
Comments are currently disabled.