
September Comprehensive Real Estate Holding Tax Exclusion and Special Case Applications: Caution Required for New Acquisitions in Adjustment-Targeted Areas
As the application period for the September Comprehensive Real Estate Holding Tax exclusion and special cases begins…
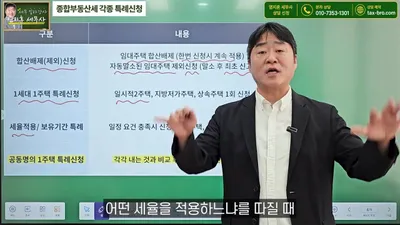
With the application period for the September Comprehensive Real Estate Holding Tax exclusion and special cases approaching, the key requirements and precautions to reduce the tax burden have been organized. According to the content of the released video, "exclusion from aggregation" is a method of excluding a house from the taxation target, while "special case application" is a method of avoiding heavy taxation by excluding the house from the count of houses owned.
Rental Housing Registration and Regional Requirements for Aggregation Exclusion
A representative type of aggregation exclusion is registered rental housing. It must be registered with both the local government and the tax office, and currently, one must comply with the mandatory rental period of 6 or 10 years and the 5% limit on rent increases. The video specifically urged caution regarding newly acquired houses within adjustment-targeted areas. For a household owning one or more houses, any house newly acquired in an adjustment-targeted area after September 14, 2018, cannot receive the Comprehensive Real Estate Holding Tax aggregation exclusion benefit, even if all other requirements are met. However, if the owner was a non-homeowner at the time of acquisition or acquired the house in a non-adjustment-targeted area, the benefit can be applied even if the area is designated as an adjustment-targeted area in the future.
There are also differences depending on the type of housing. Apartment-type private rental housing for which a registration application was made after July 11, 2020, is ineligible for aggregation exclusion. Additionally, rental houses subject to aggregation exclusion must have a standard market value of 600 million won or less in the Seoul metropolitan area and 300 million won or less in non-metropolitan areas at the time the rental begins. If the 5% rent increase limit is violated, the house may be excluded from the aggregation exclusion target for the current and following year, and the reduced tax amount and an amount equivalent to interest may be collected.
Differences Between Comprehensive Transfer and the Scope of Recognized Rental Periods
In the case of a comprehensive transfer of rental housing, the mandatory rental period recognized under tax law is based on the period actually held by the taxpayer. Regarding the perception that the previous rental business operator's rental period is succeeded during a comprehensive transfer, the video explained that if the taxpayer changes under tax law, the previous operator's rental period is not included in the mandatory rental period for aggregation exclusion. In other words, while one might avoid fines during a comprehensive transfer, the mandatory period for tax benefits must be interpreted as starting anew. Furthermore, caution is required as the reduced tax amount and an amount equivalent to interest may be collected if the house is comprehensively transferred during the mandatory rental period.
Special Case Applications for Temporary Two-House Ownership, Inheritance, and Spousal Joint Ownership
Types of special case applications that allow exclusion from the house count include temporary two-house ownership, inherited houses, low-value local houses, and spousal joint ownership. In the case of temporary two-house ownership, if a new house is acquired while an existing house is held and the existing house is disposed of within 3 years, the owner is considered a single-house owner and taxed accordingly. Regarding the Comprehensive Real Estate Holding Tax standard, unlike the capital gains tax, it is applicable if the requirement to dispose of the house within 3 years is met, even if it has not been one year since the acquisition of the new house. However, if the house is not disposed of within 3 years, the reduced tax amount and an amount equivalent to interest will be imposed.
For inherited houses, requirements such as whether 5 years have passed since the commencement of inheritance, whether the inherited share is 40% or less of the total, or whether the declared price of the inherited share is 600 million won or less, must be examined. In the case of spousal joint ownership, one can choose between paying according to each person's share or applying as a single-house sole owner to receive the basic deduction of 1.2 billion won. The video specified that the method of calculating the number of houses when applying these special cases may differ from acquisition tax or capital gains tax.
0Comments
Comments are currently disabled.