
Credit score gaps can cause 1.6 million won interest difference
Differences in credit scores can result in interest costs varying by millions of won, as a person with a 990 score pays significantly less than someone with a 300 score for the same loan amount.
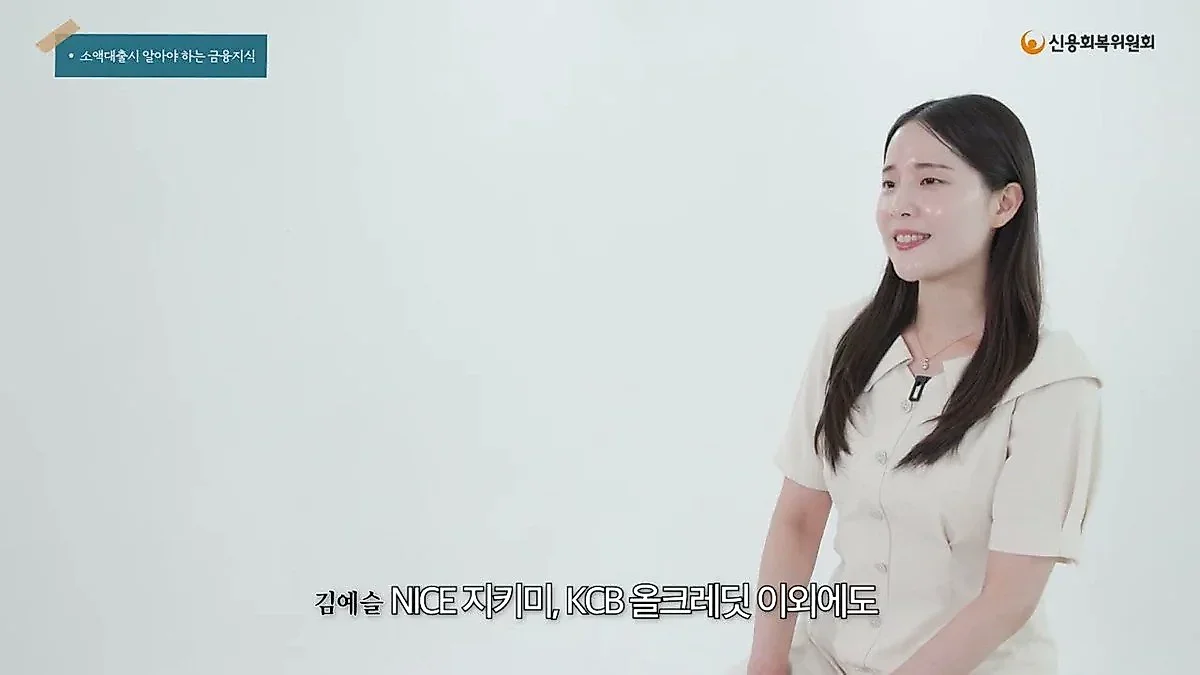
A 10 million won credit loan could cost a user with a score in the 300s nearly 2 million won in interest, which is five times the 400,000 won burden faced by those with a 990 score. Kim Ye-seul of the Credit Counseling and Recovery Service advised using primary banks and check cards to help manage these costs.
Differences in credit scores can cause loan interest costs to diverge by millions of won. While a high credit score allows for loans with low interest rates, a low score not only necessitates higher interest rates but also imposes constraints on overall economic activities, such as limited loan ceilings or difficulties in issuing credit cards.
Information provided by the Credit Counseling and Recovery Service CCRS contains essential credit management methods and loan product selection priorities for applicants considering small-sum loans. Kim Ye-seul, a senior examiner at the Credit Counseling and Recovery Service, defined credit as "using first and paying back later," noting that for an individual, it signifies debt that must be repaid.
Practical ways to raise credit scores: "The key is using a primary bank and check cards"
Credit scores are calculated by credit bureaus (CB) that collect various credit activity information of individuals, resulting in a value between 1 and 1,000. A higher score leads to more favorable financial conditions. Kim provided specific credit score management tips that can be practiced in daily life.
The first recommended method is to establish a primary bank. Consistently using a primary bank by designating a payroll account or utilizing savings and installment savings accounts is advantageous for raising credit scores and may also provide preferential interest rate benefits for future loans. Additionally, consistent use of a check card is helpful. Developing a habit of using a check card for more than 300,000 won every month for at least six months while paying the full balance can positively impact creditworthiness.
Conversely, certain behaviors to avoid are clear. One must not be delinquent on loan payments or credit card bills, even for small amounts. This applies to both loans and credit card payments. In particular, using credit card cash services, card loans, or revolving services can be interpreted as a signal of insufficient repayment ability, serving as a cause for credit score drops. Furthermore, the habit of faithfully paying public utility bills, such as the National Pension, health insurance, telecommunications, and gas, water, and electricity, can contribute to improving credit scores.
Currently, credit scores can be checked for free through credit bureaus such as NICE or KCB. Since scoring methods and weightings differ by bureau, it is advisable to check and manage scores from both. They can also be easily checked through financial platforms such as Toss, KakaoBank, Naver Pay, and Banksalad.
"A 1% difference in interest is decisive"... Questions to ask oneself before taking a loan
Before executing a loan, one must objectively check their repayment ability. Kim advised asking oneself whether the loan is truly necessary or if the funds could be secured through savings or by postponing the loan. Additionally, a specific plan must be established to ensure the loan amount is at a level that can be repaid without delinquency, including how much must be paid each month and over what period. In short, individuals must verify for themselves how much funds they can secure monthly, over what period they can repay, and whether they can repay without delinquency.
The actual difference in interest rates is starkly visible in numbers. For example, when borrowing 10 million won as a credit loan, a user with a credit score of 990 applying for a loan from a Tier 1 financial institution at an annual interest rate of 4% would pay approximately 400,000 won in interest. However, if a user with a credit score in the 300s uses a high-interest loan with an annual interest rate reaching 20%, they would face an interest burden of approximately 2 million won. This means the score difference widens the interest cost by nearly five times. Therefore, if a loan is absolutely necessary, managing credit scores to lower interest rates is essential.
There is a clear order when selecting loan products. One should first check Tier 1 financial institutions (commercial banks), followed by policy-based microfinance products for the people such as Haetsallon, Smile Microfinance, New Hope Seed, and Saitdol Loan from the Korea Inclusive Financy Agency. After that, Tier 2 financial institutions should be checked, and private moneylenders should be the very last resort. This is because skipping policy finance products to use high-interest loans can lead to a drop in credit scores and an increased interest burden, raising the risk of default.
Debt repayment strategy: "Repay in order of highest interest rates"
If one already holds loans, the order of repayment is important. Kim recommended prioritizing the repayment of products with the highest interest rates. This is the most efficient way to reduce total interest costs and accelerate credit recovery.
The Credit Counseling and Recovery Service operates customized debt adjustment programs for those experiencing difficulties with debt. By continuing to repay faithfully through debt adjustment, individuals can receive various financial benefits, including credit score increases, issuance of small-sum credit cards, special support for housing lease deposits, and additional small-sum financial support.
Meanwhile, caution is required to prevent financial fraud. If one receives loan solicitations requesting personal information or money, they should immediately stop responding and verify the facts. If financial fraud is suspected, consultations and reports can be made through the police (112), the Financial Supervisory Service (1332), or the Korea Internet & Security Agency (118). Additionally, detailed information on microfinance products for the people can be found through the Korea Inclusive Financy Agency call center (1397), and information on financial products can be checked through the Financial Supervisory Service's financial consumer information portal, FINE.
Source: original video (YouTube)
0Comments
Comments are currently disabled.