
William Bengen raises safe retirement withdrawal rate to 4.7%
William Bengen, the creator of the "4% Rule," revealed in a recent interview that the safe withdrawal rate (SafeMax) can be increased to 4.7% due to recent market conditions.
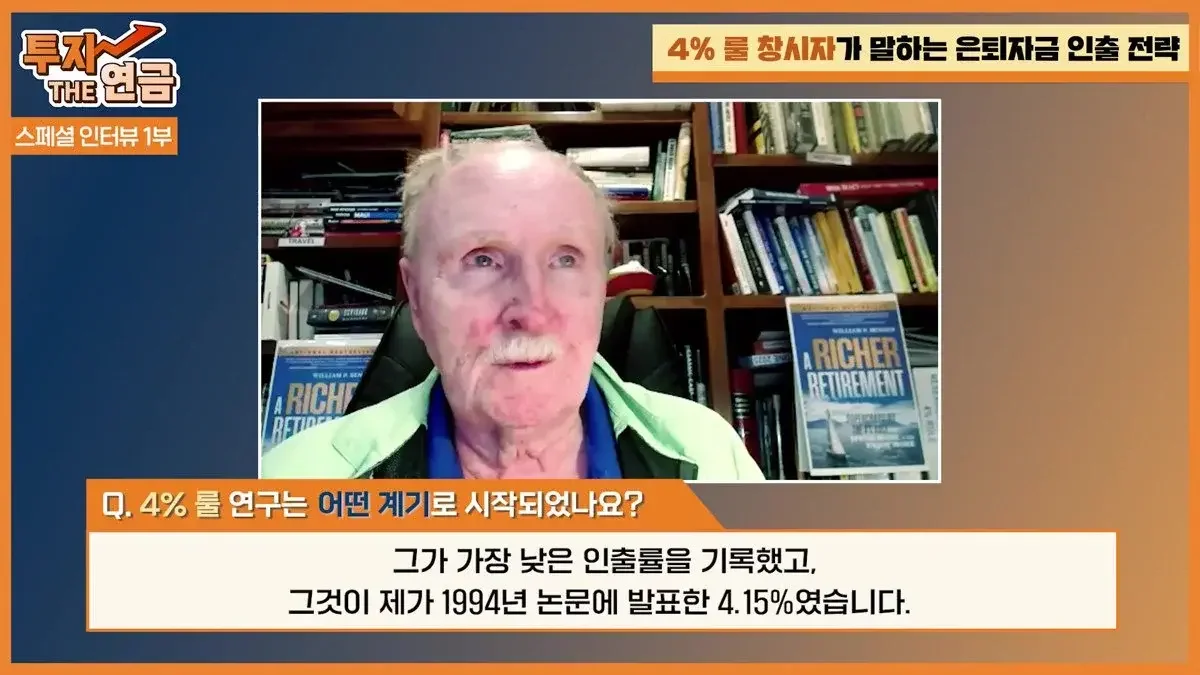
William Bengen, the creator of the "4% Rule," announced in a recent interview that the safe withdrawal rate (SafeMax) has risen to 4.7% due to a strong bull market over the last 15 years and improved asset allocation models.
The anxiety regarding when prepared retirement funds might be exhausted is a common concern for all prospective retirees. To address this, financial planners worldwide cite the "4% Rule" as a standard. William Bengen, the creator of this rule which limits the minimum withdrawal rate to approximately 4% to ensure retirement funds are not depleted, recently disclosed his research and updated withdrawal strategies through an interview in Korea.
The interview, reported by Mirae Asset Investment and Pension TV, covers Bengen's unique background—transitioning from an aerospace engineering major to a financial expert—the origins of the "4% Rule" in the early 1990s, and the basis for the recently adjusted safe withdrawal rate (SafeMax).
From Aerospace Engineering Student to Creator of the '4% Rule'
Bengen's career path is unusual. After majoring in aerospace engineering at MIT and operating his family's beverage distribution business before selling it, he studied finance, obtained his CFP certification, and became a financial planner. In the video interview, he reflected on his past, stating, "During my college years, I hoped to participate in planetary exploration such as Mars exploration, but since Mars was still a distant dream, I decided to do something other than the field I originally had passion for."
The impetus for his research began with questions from clients. Bengen recalled that while working as a financial planner in the early 1990s, he was constantly asked by clients, "How much should I save for retirement?" and "How much can I spend each year so that I don't run out of money after retirement?" At the time, no clear answers could be found in CFP textbooks, financial magazines, or the WSJ. Even when asking fellow financial planners at the time, answers varied wildly from 3% to 8%.
Bengen decided to collect data himself. Using Lotus 1-2-3 spreadsheets, he built a model based on investment returns and Consumer Price Index (CPI) data dating back to 1926. After simulating hundreds of retirement cases, he discovered that even under the worst conditions for a case of retirement in October 1968, a withdrawal rate of 4.15% could avoid bankruptcy, which became the foundation for what would later be known as the "4% Rule." He explained, however, that this figure was slightly adjusted to 4% as it became known to the public.
Not 4% of the Remaining Balance... A 'Withdrawal Method' Reflecting Inflation
Many people misunderstand the "4% Rule" as a "fixed percentage withdrawal" method where 4% of the remaining balance is withdrawn every year. However, the method proposed by Bengen is fundamentally different. Rather than a method where the withdrawal amount decreases in proportion to the remaining balance each year, it is a method where a set amount is withdrawn in the first year, and from the following year onward, the withdrawal amount is increased by the rate of inflation.
Bengen explains this as the "COLA (Cost of Living Adjustment) approach." Based on a specific ratio derived from research, withdrawals begin in the first year, and thereafter, instead of using that ratio again, the withdrawal amount is adjusted annually only by the inflation rate. This is a strategy to maintain real purchasing power and preserve the standard of living throughout the retirement period. It operates on a principle similar to how National Pension benefits are adjusted annually according to the inflation rate.
"Safe Withdrawal Rate Raised to 4.7%"... Changed Market Environment and Portfolio Strategy
Through his recently published book 'All Richer Retirement,' Bengen has upwardly adjusted the previous safe withdrawal rate figures. While the figure that assumed worst-case scenarios in the past was 4.15%, the safe withdrawal rate (SafeMax) derived from recent research has risen to 4.7%. He cited the strong bull market that has persisted over the last 15 years and more sophisticated asset allocation models as the basis. He forecasted, "Realistically, 5% to 5.5%, or even more, may be possible."
The core of his investment strategy is "asset preservation." Bengen emphasized, "Since asset loss deprives retirees of the opportunity to recover, protecting capital is the top priority." To this end, he currently manages a portfolio consisting of a total of seven asset classes, including five stocks, bonds, and cash. He added, "I may add more asset classes in the future, but according to recent research results, it appears to have reached a stage of 'diminishing returns' where adding asset classes does not greatly help in increasing returns."
In particular, he places importance on the correlation between assets. He explained, "If you can combine assets that fall when other assets in the portfolio rise, or conversely, rise when other assets fall, you can create a much smoother flow, which leads to higher withdrawal rates." Furthermore, he advised retirees to actively manage risks with the help of a third party so they can manage assets without being swayed by emotions.
Source: original video (YouTube)
0Comments
Comments are currently disabled.