
New pension guide offers tax-saving strategies for retirement investors
Tax accountant Kim Yeon-hong provides a strategic guide for investors approaching retirement to manage pension assets and minimize tax burdens through specific contribution and withdrawal methods.
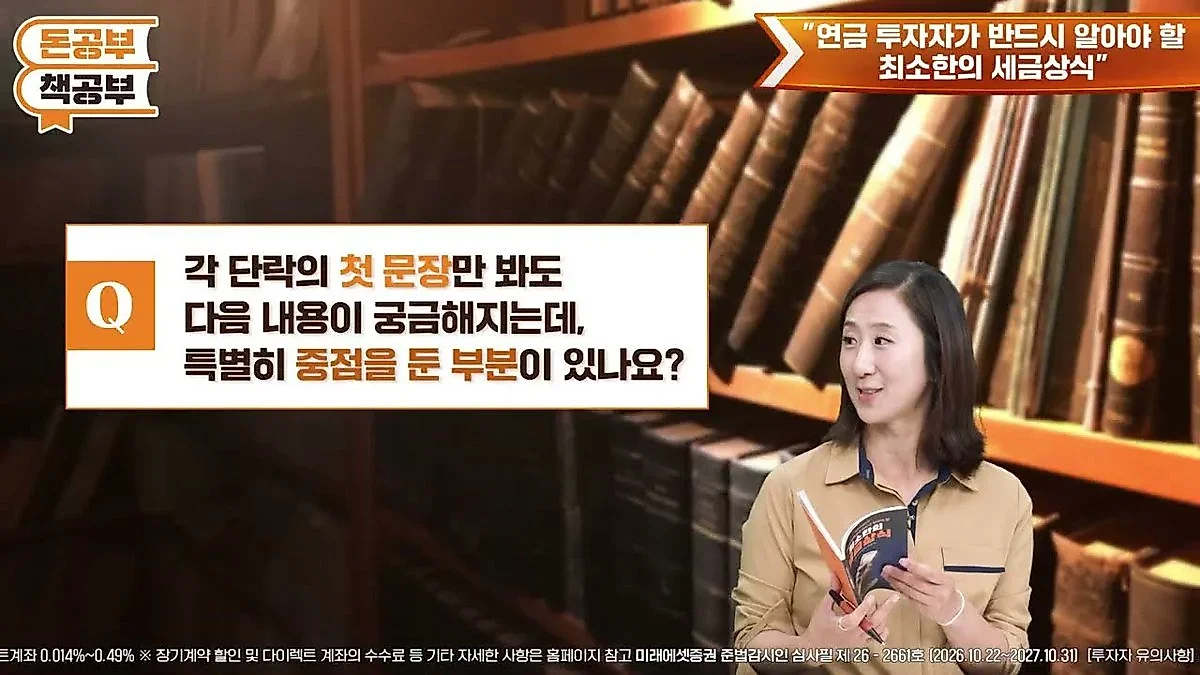
Tax accountant Kim Yeon-hong has released a practical guide to help investors manage pension assets and minimize tax burdens. The book recommends using pension accounts for monthly dividend ETFs and receiving retirement pay as a pension to avoid global financial income tax and additional health insurance premiums.
As investors approach the age of 55, many begin to focus on managing their pension assets. However, many find themselves at a loss regarding how to prepare due to the complex tax system. This is why an "action plan" that can be implemented immediately is more necessary than theoretical tax knowledge.
The "Essential Tax Basics Every Pension Investor Should Know," recently published by the Mirae Asset Investment and Pension Center, focuses on this exact point. Written by tax accountant Kim Yeon-hong of the Mirae Asset Securities Pension Consulting Team, the book contains practical tax-saving strategies based on the questions most frequently asked by clients at the time of retirement. Kim stated that through pension-related consultations and seminars, she confirmed that many clients only begin to take an interest in taxes once they reach retirement, and she wrote this book to share those insights.
Remember the numbers '3·6·9·18' if you are confused about pension contribution limits
The first hurdle for investors managing pension accounts for the first time is distinguishing between the tax credit limit and the maximum allowable contribution. To address this, Kim Yeon-hong suggests remembering the numbers '3·6·9·18.' The annual contribution limit to receive a tax credit through a pension account is 9 million won. To reach this, many investors choose to split their contributions by putting 3 million won into an IRP (Individual Retirement Pension) and 6 million won into a pension savings account.
However, it is possible to contribute more than the 9 million won tax credit limit. The total annual contribution limit for a pension account is 18 million won. The crucial point is where to place the excess contributions. Kim recommends putting surplus funds that exceed the tax credit limit into a pension savings account. This is because while withdrawals from an IRP are only permitted for legally defined reasons, withdrawals from a pension savings account are relatively free without needing a separate reason.
There is also a difference in the tax burden during withdrawal. When funds are withdrawn from a pension account, the amounts that did not receive tax credits are withdrawn first, and no tax is imposed on these amounts at the time of withdrawal. Therefore, utilizing a pension savings account is strategically advantageous when preparing for situations where a large sum of money may be needed.
Why pension accounts are more advantageous than general accounts for monthly dividend ETF investments
Recently, demand for investing in monthly dividend ETFs has been increasing to secure cash flow after retirement. In this case, the tax burden and health insurance premiums can vary significantly depending on the investment method. For example, suppose a worker in their 50s, Kim Mi-rae (pseudonym), invests 200 million won in a domestic equity monthly dividend ETF and receives 1 million won in distributions every month (12 million won per year).
If Kim receives these distributions through a general account and the total annual financial income exceeds 20 million won when combined with other financial income, she becomes subject to the global financial income tax. This not only increases the burden of the comprehensive income tax but also serves as a cause for paying tens or even hundreds of thousands of won in additional monthly health insurance premiums when transitioning from a workplace subscriber to a local subscriber after retirement.
On the other hand, if the same amount is managed through a pension account, the situation changes. Distributions generated in a pension account are excluded from the global financial income tax, and as of now, no health insurance premiums are levied on income within a pension account. Furthermore, when receiving these as a pension after age 55, if the annual withdrawal is managed to be 15 million won or less, the tax-saving effect can be maximized by applying only a low pension income tax rate of 3.3% to 5.5%.
Receiving retirement pay through a 'pension account' is the key to tax savings rather than a lump-sum receipt
The biggest concern for workers at the time of retirement is whether to receive their retirement pay as a lump sum or as a pension. Kim emphasizes that receiving retirement pay through a pension account, such as an IRP, is overwhelmingly advantageous. There are four major benefits to receiving retirement pay through a pension account.
First, the full amount can be deposited without having retirement income tax immediately deducted upon receipt. Second, a "tax deferral" effect occurs, where taxes on interest or dividend income generated within the account are postponed until the time of withdrawal. Third, if received as a pension, one can receive a reduction of 30% to a maximum of 50% of the original retirement income tax that would have been owed. Finally, income within a pension account is excluded from health insurance premium assessments, reducing the burden when transitioning to a local subscriber after retirement.
However, there are points to be cautious of. After all retirement pay resources have been withdrawn, when withdrawing the principal that received tax credits and the investment returns, the annual limit of 15 million won must be observed. If the withdrawal amount exceeds 15 million won per year, it must be combined with other income for comprehensive taxation or a single tax rate of 16.5% must be selected, necessitating wisdom in adjusting the scale of withdrawals according to one's income situation.
Meanwhile, Kim also presented "5 Commandments for Retirement Tax Savings" for workers. The main points include: ▲Receiving performance bonuses through the DC type to save on health insurance premiums; ▲Saving on taxes by using tax settlement during past interim settlements; ▲Receiving retirement pay through a pension account instead of a lump sum; ▲Withdrawing within the set limits; and ▲Minimizing taxes by withdrawing at least 10,000 won every year from the pension account after age 55.
Source: original video (YouTube)
0Comments
Comments are currently disabled.