
Switching pension insurance to funds could quadruple retirement assets
A difference in management strategies between pension insurance and pension funds can lead to a fourfold difference in accumulated assets, according to Hong Chun-uk's Economics Lecture Notes.
Retirement assets could reach nearly 200 million won from a 73 million won investment if managed through funds rather than insurance, according to a video from Hong Chun-uk's Economics Lecture Notes. While pension savings insurance currently averages a 1.8% annual return, securities firm funds have shown an average yield of approximately 5.5%.
Only four out of ten people who open pension accounts actually fund and manage them. According to statistics from the Financial Supervisory Service, the ratio of pension account holders who actually deposit and utilize funds is at the 40% level. The remaining 60% have only created accounts and are missing out on year-end tax settlement benefits.
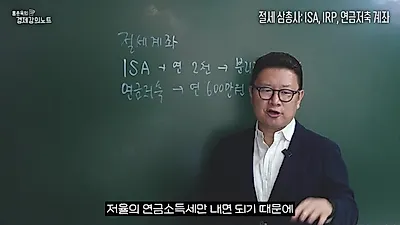
A recent video from Hong Chun-uk's Economics Lecture Notes covered the differences and efficient management strategies for the "three musketeers of tax-saving accounts" for wage earners: ISA, pension savings, and IRP. In particular, it emphasized that depending on how they are managed, retirement assets can differ by more than two times, and by as much as four times.
ISA for lump-sum accumulation, pension savings and IRP for retirement preparation
The three accounts serve different purposes. ISA is an account specialized for creating a lump sum through financial technology. It allows annual deposits of up to 20 million won (which could expand to 40 million won upon tax law revision), and provides tax-free benefits of 2 to 4 million won on interest and dividend income. For profits exceeding the limit, a 9.9% separate taxation applies, which offers the advantage of avoiding the burden of comprehensive financial income taxation—which is combined with earned income and results in higher tax rates—or increases in health insurance premiums. It is also characterized by the fact that there are no penalties for mid-term withdrawals within the deposited principal.
On the other hand, pension savings and IRP are accounts for accumulating retirement funds. For pension savings, tax credits can be received up to 6 million won annually, and if including IRP, a total of 9 million won can be received. IRP is also used for managing retirement pay; instead of withdrawing retirement pay immediately and paying retirement income tax, receiving it through an IRP and collecting it as a pension can significantly lower the tax burden. However, because penalties may occur upon mid-term withdrawal in exchange for year-end tax settlement benefits, users must be cautious when joining. Hong recommended a strategy where the younger generation focuses on ISA, while those in their 40s and 50s increase the proportion of pension savings and IRP.
Switching from insurance to funds can quadruple assets
The gap in returns based on management methods is stark. Hong assumed a scenario where 10 million won is managed for 20 years at an annual return of 7%. In a general account, after deducting the 15.4% annual interest and dividend income tax, it would become approximately 32 million won, but by utilizing a pension account that defers taxes, approximately 38.68 million won can be created. The results diverge even more as the difference in returns increases.
Currently, about 60% of pension savings reserves are tied up in insurance products, and the average return on pension savings insurance remains at around 1.8% per year. In contrast, pension savings funds at securities firms have been shown to yield an average of about 5.5%. If 73 million won is managed for 20 years, insurance would result in approximately 104 million won, but managing it with funds could form assets approaching 200 million won. Hong advised, "If you are worried about the taxes incurred upon cancellation, you should consider transferring to a pension savings fund through the account transfer system."
Solving withdrawal concerns before age 55 by utilizing 'excess contributions'
The biggest concern regarding pension accounts is that funds are tied up until age 55. However, Hong presented two solutions. The first is to utilize pension savings funds at securities firms. At securities firms, it is possible to take out loans at a level of 60–70% using pension assets as collateral, allowing for responses when urgent funds are needed.
The second is to utilize amounts deposited in excess of the tax credit limit. Pension savings and IRP allow for annual deposits of up to 18 million won. The remaining 9 million won, which exceeds the 9 million won tax credit limit, incurs no penalty upon withdrawal. Therefore, if one withdraws funds sequentially starting from the amounts that did not receive tax credits, funds can be used before age 55 without a tax burden. Hong emphasized, "As retirement approaches, one should maximize the limits of pension savings and IRP to enjoy both tax-saving effects and long-term investment effects simultaneously."
Source: original video (YouTube)
0Comments
Comments are currently disabled.