
French Government Bond Yields Surpass 4.87%... A Vicious Cycle Trapped by Interest Burdens Amid Stagnant Growth
French government bond yields have reached 4.87%, the highest level since 2002, amid growing fiscal crisis concerns and a widening interest rate gap with Germany. The country faces a structural crisis where low growth prevents it from offsetting rising debt with economic expansion.
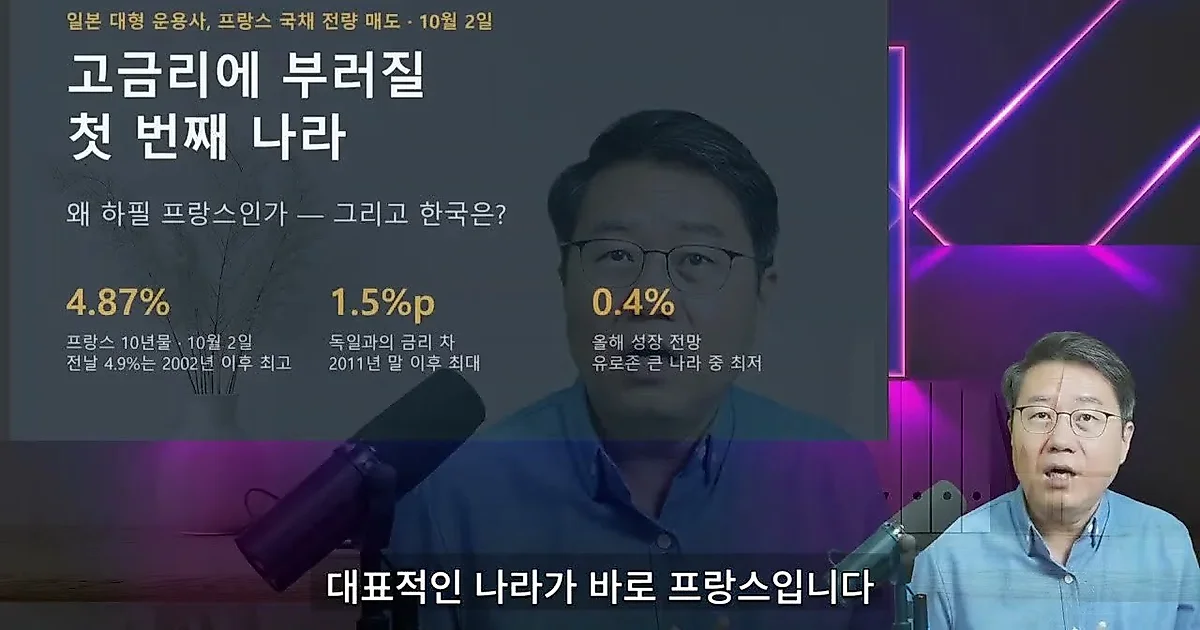
As the upward trend in United States Treasury yields continues, French government bond yields have recorded 4.87%, the highest level since 2002, increasing concerns over a fiscal crisis. In particular, France's interest rate rise is faster than that of the United States, and the interest rate gap with Germany is also showing a pattern of widening. According to the video, France's growth forecast for this year is 0.4%, the lowest among major eurozone countries, meaning it faces structural limitations in attempting to offset increased debt through economic growth.
The Exit of Japanese Capital and Rising Risk Premiums
The instability of the French government bond market is clearly evident in the movement of Japanese capital. Sumitomo Mitsui DS Asset Management, a large Japanese asset management company, announced that it has sold all its French government bonds held in its global bond funds and moved those funds into German government bonds and Japanese short-term government bonds. It appears that the management company moved funds to Germany and Japan, which are safer even if interest rates are lower, based on the judgment that fiscal concerns in France are serious.
In fact, while the interest rate difference between Germany and France was at the 0.5% point level last January, the gap widened sharply to 1.5% points entering September. This means that as the risk of French government bonds increases, investors are demanding higher interest rates. This risk premium is not staying in France but is showing a pattern of spreading to Southern European countries such as Italy and Greece.
A Vulnerable Structure with 55% Foreign Ownership and the Risk of Hedge Fund Sell-offs
The vulnerability that differentiates the French government bond market from other advanced nations is the high proportion of foreign ownership. Unlike Japan, where the foreign ownership of government bonds is at 13%, and South Korea, where it is at the 26% level, foreigners hold 55% of all French government bonds. In particular, the amount of French government bonds held by Japanese investors reaches 75 billion dollars, and hedge funds account for half of the foreign-held volume.
Due to the nature of hedge funds investing using leverage, there is a high possibility that a rise in interest rates, which causes government bond prices to fall, could lead to large-scale sell-offs. The video explains that as Japan's 10-year government bond yield approaches 3%, a trend of Japanese investors withdrawing funds is appearing as the interest rate gap with French government bonds narrows to the 1.8% point level. In fact, the net selling of overseas bonds by Japanese investors reached 3.42 trillion yen this February.
The Vicious Cycle of Fiscal Deficit Created by Low Growth and High Interest Rates
The seriousness of France's fiscal crisis is added by the fact that it is caught in a vicious cycle of 'stagnant growth' and 'increasing debt.' France's debt-to-GDP ratio is 117%, significantly exceeding the eurozone average of 88.9%. Unlike Greece, which overcame its past high debt ratio through fiscal reforms to lower the ratio to 143% and achieve a fiscal surplus, France's debt ratio, which was 115% in 2020, has actually increased to 117% as of 2026.
Currently, France's fiscal deficit is recording 5% of GDP, and three-fifths of this deficit amount is being used to cover interest costs. It is a structure where the interest burden increases due to high interest rates, and debt must be issued again to pay the interest. France does not have its own central bank and needs support from the ECB, but it also faces institutional constraints where it may be difficult to receive financial support from the ECB if it does not comply with fiscal rules.
0Comments
Comments are currently disabled.