
Net worth of 1 billion won places individuals in top 10% in South Korea, says Dr. Hong Chun-wook
Dr. Hong Chun-wook shares an asset design method and investment strategy to reach a net worth of 1 billion won, noting that such an amount places individuals in the top 10% of South Korea's wealth distribution.
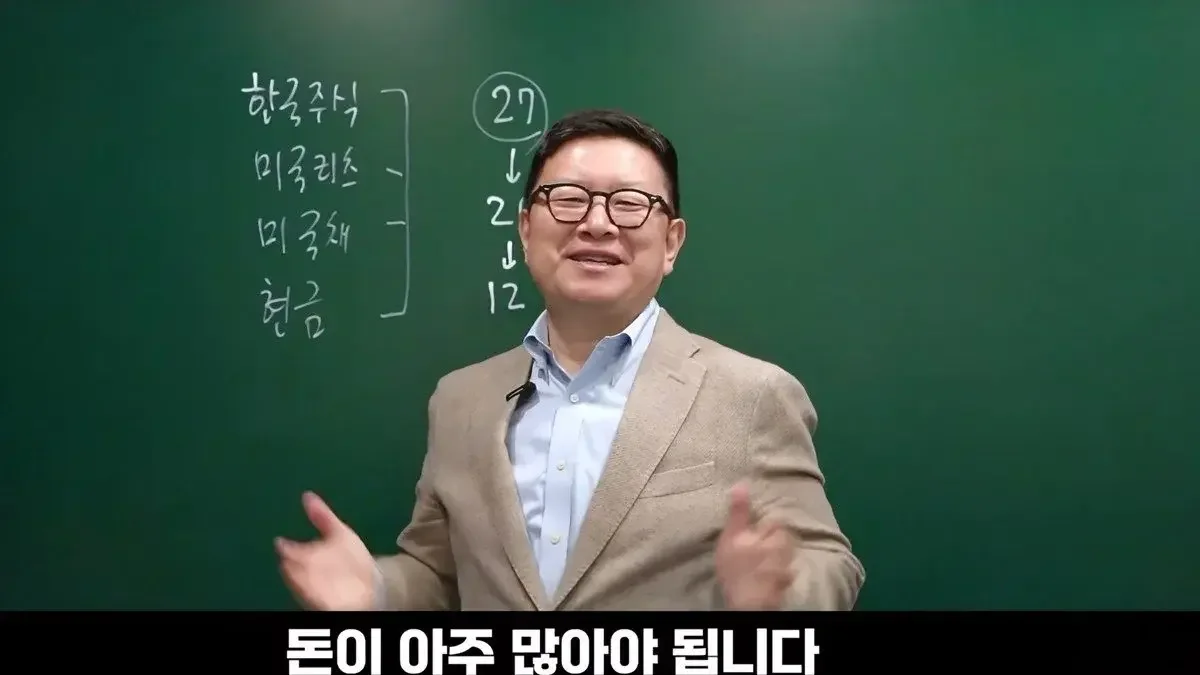
As of 2025, the cutoff for the top 10% in South Korea is 1.1 billion won, according to Dr. Hong Chun-wook. Using an "Investment Quadrant Method," a person saving 4 million won monthly could reach a 1 billion won net worth in just 12 years.
In South Korea, possessing a net worth of 1 billion won places an individual in the top 10%. While some online criticisms suggest that 1 billion won is insufficient to guarantee retirement, statistical figures show it remains a very high economic status. As of 2025, the cutoff for the top 10% in South Korea is 1.1 billion won, while the top 5% stands at 1.63 billion won and the top 1% at 3.5 billion won.
The core of the investment design method shared by Dr. Hong Chun-wook begins with accurately identifying one's current financial status. Dr. Hong stated that his family checks their asset status every year at the beginning of the year through an Excel file titled "Mom and Dad's Dream." This file records total assets, including housing, liabilities, as well as annual income and expenditures. After confirming the net worth, the method involves calculating the expected time to reach a goal by predicting how many percent the assets can grow based on the annual surplus cash flow.
Scenarios for reaching 1 billion won based on monthly savings
As a realistic investment strategy, Dr. Hong proposed the "Investment Quadrant Method," which allocates 25% each to South Korean stocks, United States REITs, United States Treasuries, and South Korean cash. Based on this strategy, simulations show how the time required to reach a net worth of 1 billion won changes depending on the monthly savings amount.
First, if a person just starting their career saves 1 million won per month using the Investment Quadrant Method, it takes approximately 27 years to accumulate 1 billion won. If the monthly savings are increased to 2 million won, the period is shortened to 21 years. Dr. Hong explained that this is a sufficiently achievable figure considering the typical life cycle of staying in a primary job from the start of professional life until the late 40s.
For dual-income households with greater saving capacity, the results are even more dramatic. If one person's income is used for living and education expenses while the other person's entire income is focused on investment, saving 4 million won per month reduces the period to reach 1 billion won to just 12 years. Dr. Hong identified three major principles for wealth formation: ▲saving as much as possible (controlling expenditures), ▲consistent investment with a long-term perspective of about 20 years, and ▲efforts to increase income itself (self-development during youth).
Savings interest rates have limits; 'Investment is a necessity, not an option'
A strategy of growing assets solely through bank savings faces the barriers of inflation and taxes. Dr. Hong compared the performance of the Investment Quadrant Method against South Korean savings interest rates based on a 100 million won benchmark starting from the year 2000. If the Investment Quadrant Method had been utilized during that period, assets would have approached approximately 800 million won, whereas relying on savings interest rates at the 3% level would have left assets at approximately 200 million won.
While savings have the strong advantage of no risk of principal loss, they fall significantly behind investment strategies in terms of the compound interest effect. Particularly in an environment where the policy interest rate is in the 3% range and the consumer price inflation rate exceeds 2%, real returns are bound to be low. When the 15.4% interest income tax is also considered, the appeal of savings decreases further.
Dr. Hong emphasized, "In a world where interest rates are lower than inflation, investment is a necessity, not an option." He analyzed that while the Investment Quadrant Method involves ETF fees and trading costs occurring during the annual rebalancing process, it is relatively more cost-efficient compared to the definitively occurring interest income tax. He explained that the key to growing assets is to explore and study strategies that can generate stable returns while minimizing losses.
Source: original video (YouTube)
0Comments
Comments are currently disabled.