
South Korean potential growth rate could reverse 40-year downward trend
Professor Kim Kwang-seok analyzes potential shifts in South Korea's potential growth rate and the mechanisms of bond yields, oil prices, and exchange rates that will influence future inflation.
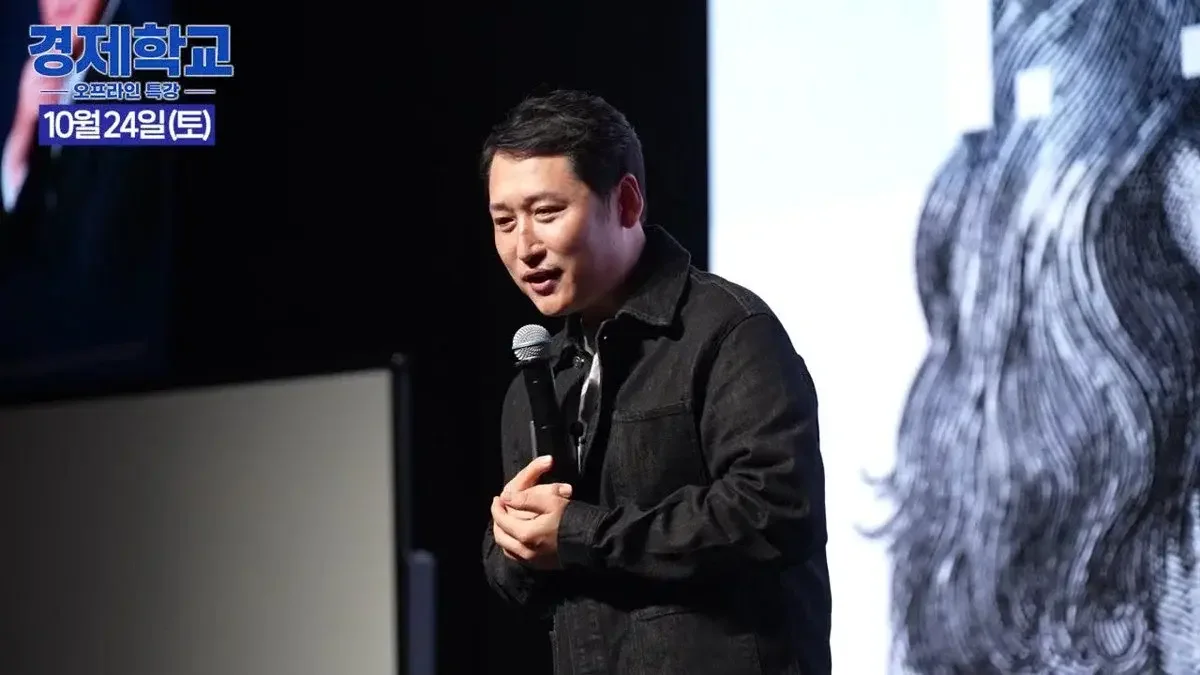
Professor Kim Kwang-seok noted that South Korea's potential growth rate could be adjusted upward for two consecutive years, potentially reversing a downward trajectory seen over the past 40 years. He also predicted that the exchange rate will likely maintain a "strong dollar new normal" at the 1,300 won level rather than returning to 1,150 won.
The South Korean economy is facing a "reversal" phenomenon for the first time in 40 years. During a recent monthly special lecture for Economy School, Professor Kim Kwang-seok noted the possibility that South Korea's potential growth rate could be adjusted upward for two consecutive years, an unusual trend that would reverse the downward trajectory seen over the past 40 years.
The 'Crowding-out Effect' of rising bond yields and monetary policy mechanisms
The movement of government bond yields, which acts as the gravity of the economy, is a key factor determining volatility in asset markets. Professor Kim explained that a rise in government bond yields does not necessarily mean a hike in the base interest rate; rather, it is often a result of the market pricing in anticipated rate hikes. This is a fundamental mechanism of monetary policy, as rising market interest rates can slow the economy even if the Federal Reserve does not explicitly raise the base rate.
The "crowding-out effect" occurring during this process leads to a contraction in private sector investment. As government bond yields rise, the burden of issuing corporate bonds increases for companies, eventually leading to a "separation of the wheat from the chaff" where the market reorganizes around high-quality companies capable of handling high interest rates. Consequently, these elevated rates serve to curb inflation by suppressing aggregate demand.
Correlation between international oil price growth rates and 2027 inflation forecasts
When judging inflation, the critical indicator is the "year-on-year growth rate" rather than absolute prices. Professor Kim diagnosed that while international oil prices are currently hitting previous highs due to supply shocks, the future growth rate is likely to slow down. Even if oil prices remain at high levels, if the year-on-year growth rate converges toward 0% or records a negative value, it will act as a factor in lowering inflationary pressure.
He emphasized that after oil prices peak, they historically tend to return to previous levels or decline, citing the case where oil prices surged in 2022 but recorded a negative growth rate of 17% in 2023. Furthermore, citing the concept of "Intensity" mentioned in the IMF economic outlook report, he presented the decreasing proportion of energy's contribution to GDP as a basis for price stability.
Exchange rates and stock markets amidst volatility
Professor Kim also addressed specific trends in major financial indicators, including exchange rates and the stock market. He predicted that even if the exchange rate peaks and retreats, it will not rapidly stabilize to the historical benchmark of 1,150 won, but will instead maintain a "strong dollar new normal" at the 1,300 won level. Similarly, while government bond yields are expected to pass their peak and fall, he maintained the view that the economy will enter an era of medium interest rates rather than returning to the low-interest-rate era of the past.
Regarding the stock market, he analyzed that while the United States market may show strong liquidity-driven trends, the South Korean market is likely to remain relatively within a box range. He suggested that market volatility could increase during periods of massive uncertainty, such as the U.S. presidential election.
Source: original video (YouTube)
0Comments
Comments are currently disabled.