
Business owners can use estimated filing to reduce interim tax burdens
Business owners experiencing a significant decline in performance during the first half of the year can utilize the "estimated interim tax payment filing" system to recalculate their taxes based on actual performance rather than the previous year's figures.
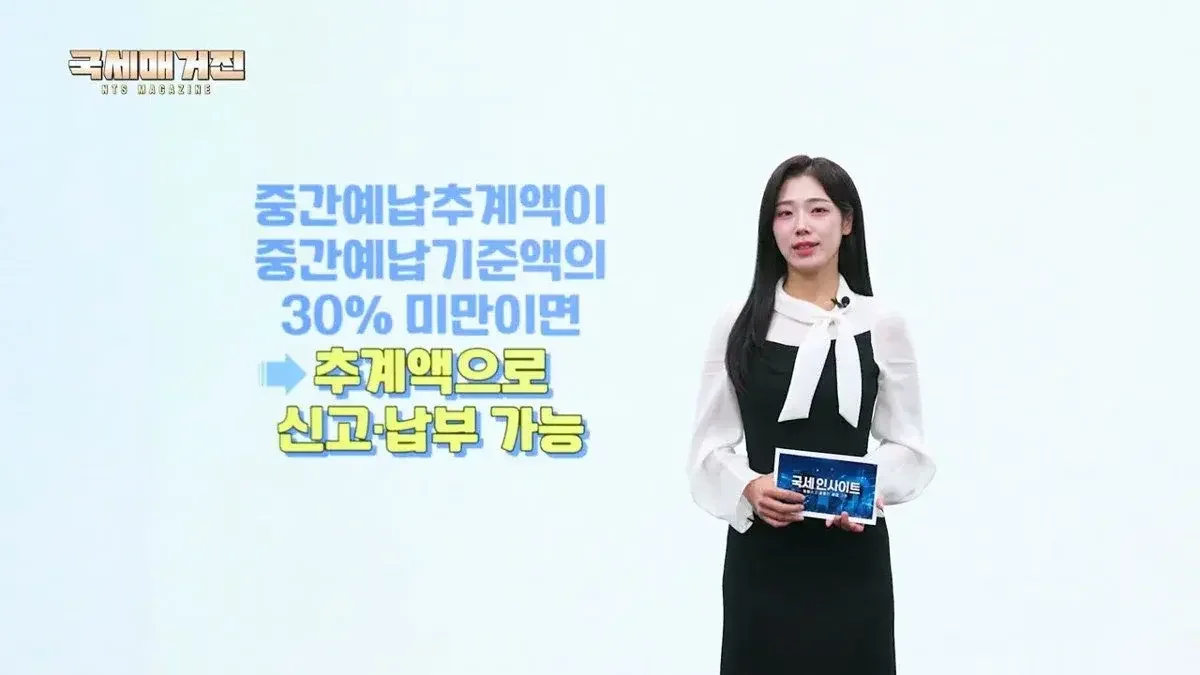
The National Tax Service announced that business owners with a significant drop in first-half revenue can use an estimated filing system to recalculate taxes. This option is available if the recalculated amount is less than 30% of the standard notified amount.
For business owners whose performance in the first half of this year has decreased significantly compared to last year, the interim comprehensive income tax amount notified based on last year's performance may pose a heavy burden. According to information provided by the National Tax Service, in such cases, owners can utilize the "estimated interim tax payment filing" system to recalculate taxes by reflecting actual performance from the first half of the year.
Recalculate tax amount with 'estimated filing' if revenue drops sharply
Standard interim comprehensive income tax is calculated and notified based on the comprehensive income tax amount finalized in the previous year. However, if business performance from January to June this year has noticeably decreased compared to the previous year, owners can recalculate the tax amount based on first-half performance instead of paying the notified amount. This is known as "estimated interim tax payment filing."
According to the explanation in the video, if the amount calculated through estimated filing is less than 30% of the existing interim tax standard amount, the business owner or a tax agent can organize the first-half revenue and expenses to report and pay according to actual performance. While this can reduce the excessive tax burden, books and supporting documents proving first-half revenue and business expenses must be thoroughly organized for accurate calculation.
In particular, if one chooses estimated filing, unlike the standard method where the National Tax Service calculates and notifies the tax amount, the business owner must directly recalculate the first-half revenue and business expenses based on books and supporting documents. Therefore, it is important to manage related data faithfully on a regular basis. This is because even if an expense is related to the business, if it is not recorded in the books or lacks proper supporting documents, it may not be recognized as a necessary expense, which could increase taxes.
Ease financial pressure with 'installment payments' for amounts exceeding 10 million won
An installment payment system is also operated for business owners who find it difficult to pay a large tax amount all at once. However, not all business owners are eligible; it is applicable only when the interim tax amount exceeds 10 million won. The criteria for installment payments are applied differentially depending on the scale of the tax amount.
If the interim tax amount exceeds 10 million won but is 20 million won or less, 10 million won must be paid within the payment deadline, and the remaining excess amount can be paid in installments within two months. For example, if the interim tax amount is 15 million won, 10 million won is paid within the deadline, and the remaining 5 million won is paid in installments by February 1, 2025.
If the interim tax amount exceeds 20 million won, installment payments of up to 50% of the total tax amount are possible. A business owner with a tax amount of 30 million won can pay at least 15 million won first and then pay the remaining 15 million won in installments. The same installment payment benefit can be received even if the tax amount calculated through the aforementioned estimated filing exceeds 10 million won.
Strict adherence to deadlines and management of supporting documents is essential
Receiving an interim tax notice does not mean one can decide to pay everything at once during the final comprehensive income tax filing next May. If the notified amount is not paid within the deadline without choosing estimated filing or applying for installment payments, a late payment penalty will occur, which may actually increase the tax burden. If financial circumstances are difficult, payment can be made via credit card, but it should be noted that credit card processing fees will be incurred in this case. Additionally, if it is difficult to transfer directly to the account stated on the notice, easy payment services can be used.
Business owners planning for estimated filing should pay more attention to regular book-keeping and the management of supporting documents. This is because even if an expense is related to the business, if it is not recorded in the books or lacks proper supporting documents, it may not be recognized as a necessary expense, which could increase taxes. Since the organized data will be used not only for this interim payment but also for the comprehensive income tax filing next May, it is recommended to develop a habit of steadily organizing books and supporting documents.
If there is an objection because the contents of the notified interim tax amount differ from the actual situation, an objection, request for examination, or request for adjudication can be filed through appeal procedures within 90 days from the date the notice was received. If the notified information differs from the actual situation, one should not ignore it and should check the relevant procedures within the set period.
Source: original video (YouTube)
0Comments
Comments are currently disabled.