
Hong Chun-uk proposes asset allocation strategy to manage retirement pensions
Dr. Hong Chun-uk advises against impulsive asset adjustments during market volatility, recommending a diversified strategy across asset classes, regions, and currencies to ensure long-term stability.
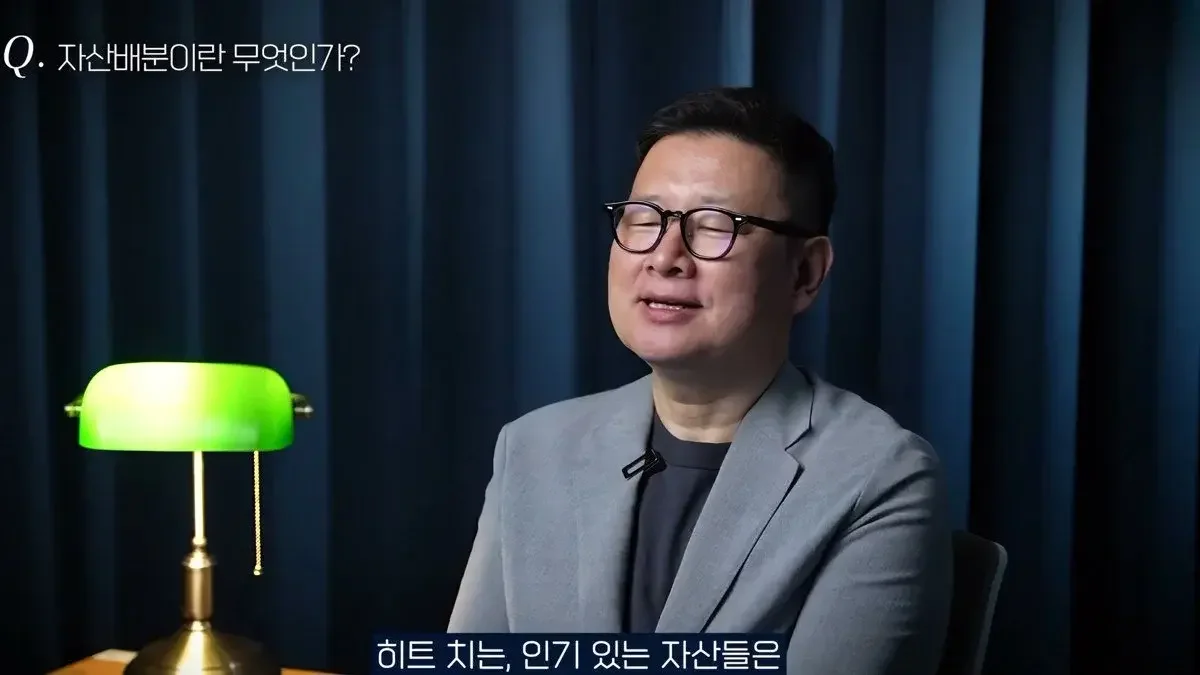
Dr. Hong Chun-uk advised investors to use triple diversification across regions, assets, and currencies to maintain psychological stability and long-term returns during market volatility. He suggested that regular rebalancing and utilizing tax-advantaged accounts like ISA can help mitigate losses and manage retirement assets more effectively than basing stock weights solely on age.
As volatility in domestic and international stock markets increases, the management of retirement assets, including retirement pensions, has become a critical issue. Investors with high stock concentrations in their accounts often face psychological pressure during market downturns, making them susceptible to the temptation of making arbitrary adjustments to their asset weights. However, experts warn that rapid adjustments driven by market fear can actually undermine long-term returns.
According to a lecture by Dr. Hong Chun-uk delivered via Hong Chun-uk's Economics Lecture Notes, the core of asset allocation lies in "combining assets that move differently from one another." Citing historical examples, Dr. Hong emphasized that asset values fluctuate differently depending on the period. During the stagflation of the 1970s, gold was the premier asset; during the 1997 foreign exchange crisis, those holding US dollars held an advantage; and during the 2008 global financial crisis, when the US government implemented quantitative easing, US long-term bonds provided the best returns.
"It is impossible to predict what the next crisis will be or which asset will be promising," Dr. Hong explained. "Therefore, because it is unknown which asset will rise and when, one must diversely hold assets that have different directions of movement and different levels of crisis resistance." He explained that simply splitting investments between Samsung Electronics and SK hynix is merely stock diversification, not asset allocation; true asset allocation involves diversifying across different types of assets such as stocks, bonds, gold, and real estate.
Defending against volatility through triple diversification of region, asset, and currency
How, then, should assets be divided? Dr. Hong proposed three dimensions of diversification. The first is asset class diversification. Rather than just holding Korean stocks, investors should divide stock markets by region—such as the US and China—and mix stocks with gold, US REITs, and bonds. The second is regional diversification, which involves looking globally rather than concentrating on a specific country. The third is currency diversification. Dr. Hong advised, "It is better not to engage in currency hedging." This is because exchange rates tend to move in the opposite direction of Korean asset prices, so diversifying into various currencies like the US dollar or the rupee can maximize the diversification effect.
The greatest benefit of such asset allocation is that it enables "long-term investment." If market volatility is too high, investors may fail to overcome fear and exit the market. However, by reducing the scale of losses through asset allocation, investors can maintain psychological stability even during economic crises and possess the patience to seize better investment opportunities.
"National Pension losses are due to lack of rebalancing"... Regular weight adjustment is essential
Once assets are divided, the next step is "rebalancing." Dr. Hong emphasized the importance of rebalancing by mentioning cases where the National Pension suffered massive losses at market peaks. For example, if an investor adopts a five-way asset division allocating 20% to each asset, but a specific asset (such as Korean stocks) surges to 50%, a process is required to sell the excess 30% to buy other undervalued assets.
There are two main methods for rebalancing: "opportunistic rebalancing," performed whenever weights deviate from a target range, and "periodic rebalancing," performed at set times once or twice a year. Dr. Hong explained the impact of weight adjustment on market stability and portfolio balance, stating, "If the National Pension had appropriately sold off when its domestic stock weight became excessively high, it would have had the capacity to more aggressively purchase during recent market crashes."
Retirees facing retirement should consider investment inclination rather than age
Regarding the common question of whether one should reduce stock holdings as retirement approaches, Dr. Hong took a cautious stance, saying, "I don't think basing it on age is quite right." The answer varies depending on an individual's investment inclination and the level of pension prepared. If a stable pension, such as the Government Employees Pension or the Private School Teachers Pension, is secured, there is no need to drastically lower the stock weight.
Furthermore, retiring does not mean stopping investment. Stocks are one of the assets with the highest returns among all asset classes. Even if retirement is near, if a person is in a situation where active saving and installment investing are still possible, a strategy of increasing stock weight may be effective. Ultimately, decisions should be made by comprehensively considering one's investment inclination, pension preparation status, and the ability to invest over the coming years.
Finally, Dr. Hong recommended actively utilizing pension savings accounts or ISA (Individual Savings Account). While retirement pensions have a 30% limit on safe assets, pension savings and ISA allow for much freer asset allocation. In particular, these tax-advantaged accounts provide an optimal environment for executing asset allocation strategies because they carry almost no tax burden arising from the rebalancing process.
Source: original video (YouTube)
0Comments
Comments are currently disabled.