
US employment remains resilient despite warnings of shrinking consumption
While the US economy shows resilience through strong employment data, a decline in real wages and weakening consumption could lead to an economic slowdown and interest rate cuts in the second half of next year.
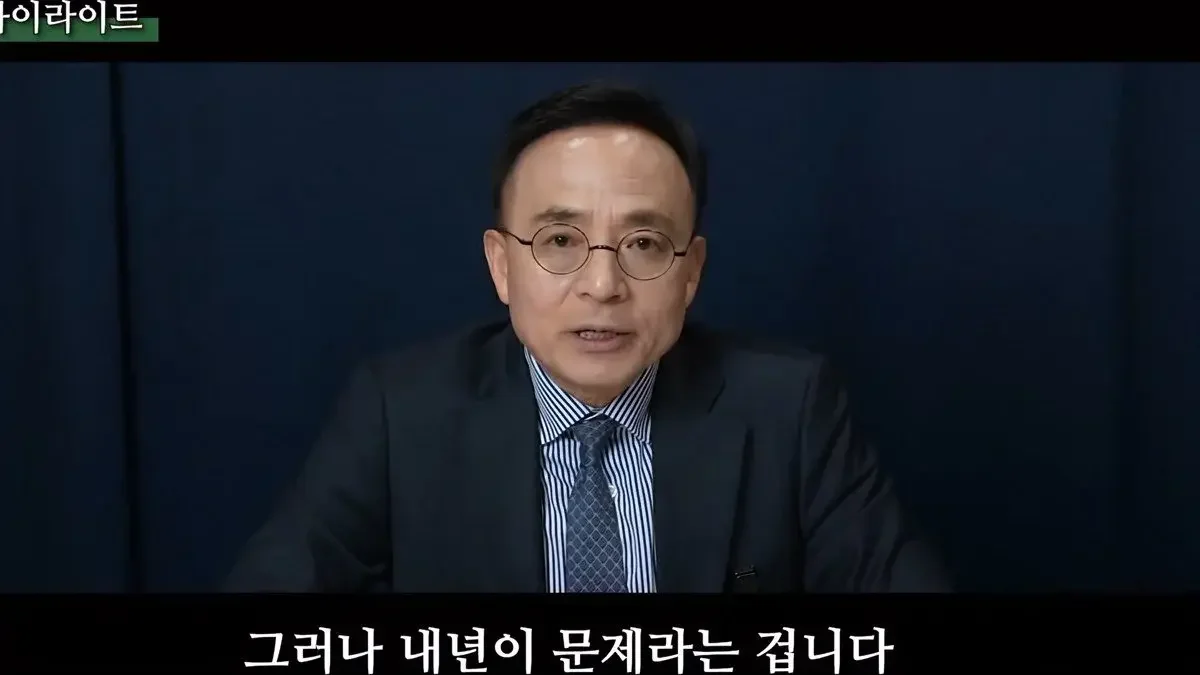
While October employment grew by 165,000 jobs, exceeding market expectations, negative real wages and shrinking consumption could trigger an economic slowdown and interest rate cuts in the second half of next year.
The US economy is demonstrating strong resilience based on robust employment indicators, but forecasts suggest an economic slowdown may emerge toward the second half of next year due to shrinking consumption. Although employment data exceeded expectations, proving economic elasticity, analysis suggests that real wages have turned negative as inflation outpaces wage growth, which could hinder future consumption.
According to the analysis provided by Professor Kim Yeong-ik, US employment data for October significantly exceeded market expectations. While experts originally estimated an increase of 65,000 jobs, the actual result was an increase of 165,000, showing a 100,000-person gap from the forecast. The unemployment rate also supported the strength of the US economy, recording 4.1%, which was lower than the market expectation of 4.2%. Kim described the US employment market as "very resilient," citing the massive recovery following the 2020 COVID-19 pandemic when companies reduced employment by 21.87 million people in just two months before rapidly recovering by 280,087,000 people (based on video audio). The average employment increase from January to October this year stands at 86,000, which is lower than 2023 but remains below the 2024 average of 166,000. The backbone of employment continues to be driven significantly by the private sector and the service industry.
The link between falling real wages and shrinking consumption
While the surface appearance of employment indicators is favorable, negative signals are being detected in terms of quality. First, as the wage growth rate slowed to 3.1% compared to the same month last year, real wages turned negative because inflation exceeded this rate. This directly leads to a decline in household purchasing power. Kim diagnosed that "since real wages are in the negative, households have been spending more than their income growth, resulting in low savings rates, and when combined with the burden of household interest due to high interest rates, there is a high possibility that consumption will contract."
In particular, the direction of consumption, which accounts for 69% of US GDP, is a key factor. Analyzing long-term trends in US consumption, Kim analyzed that signs are appearing of consumption falling below its trend. He forecasted that "consumption is highly likely to fall significantly below the trend next year, which will lead to a slowdown in corporate sales and cause companies to reduce employment." This concern is supported by the fact that the duration for the unemployed to find new jobs has recently increased to 27 weeks, making it increasingly difficult to find new work. Additionally, although the 12-month moving average unemployment rate in the US has shown a recent decline over several months, Kim believes the unemployment rate is likely to rise again in the future.
Possibility of a December rate hike and a turning point in the second half of next year
Regarding the direction of monetary policy, a flow is expected where short-term hikes intersect with mid-to-long-term cuts. Citing robust employment and persistently high inflation, Kim predicted that the Federal Reserve is highly likely to raise interest rates at the upcoming FOMC in December. This is because the Personal Consumption Expenditures (PCE) inflation, which the Federal Reserve targets as a primary monetary policy goal, has recently remained in the mid-to-high 3% range, and the October Consumer Price Index (CPI) is also expected to remain in the high 3% range. Major investment banks (IBs) also lean toward a December rate hike, with 78% of the market favoring it. The current upper limit of the federal funds rate is 4%, and many IBs forecast one more rate hike in March next year.
However, the policy direction may change in the second half of next year. Aligning with the views of some IBs such as Citi, Kim forecasted that the Federal Reserve is highly likely to cut interest rates starting from the second half of next year, when the slowdown in GDP growth due to shrinking consumption becomes visible. He explained, "If we estimate the appropriate interest rate through the Taylor Rule, interest rates will rise through the fourth quarter, but next year, inflation will decrease due to the contraction in demand, leading to a period of interest rate cuts." Citi has presented a minority view that after raising rates this time, they could maintain them until March next year and then potentially cut rates in June and September of next year.
Overvalued stock prices and credit spread warnings
Kim raised voices of caution regarding financial market volatility. He pointed out that current US stock prices are in a significantly overvalued territory based on several indicators, such as PER and Tobin's Q. In particular, he analyzed that US stock prices, centered around the Nasdaq, have entered a structural downward phase due to the AI bubble debate and the aftermath of high interest rates. He stated, "The US 10-year Treasury yield acts as the discount rate for the global stock market, and due to high interest rates, a correction centered on technology stocks is occurring." The recent 10-year Treasury yield rose to 5.3% before falling to a level slightly below 5%, but Kim judged that the vicinity of 5.3% was the peak of this upward movement.
He identified the 'credit spread' as a key indicator to detect market crises. Kim noted that as credit issues have emerged among some US AI companies recently, the credit spread is rapidly rising toward its long-term average of 0.52%. He warned, "The trend of rising credit spreads suggests that serious problems could occur in the US economic financial market," and urged responding to market changes through indicators that can be checked daily. Additionally, political uncertainty following the inauguration of the Trump administration (related to the TACO Index) was also mentioned as a major variable for the market.
Source: original video (YouTube)
0Comments
Comments are currently disabled.